Tag: real estate

  • Villa vs. Apartment: Which Home Fits Your Life and Wallet?

    Villa vs Apartment: Which for You? | Andrew Brown

    Choosing between a vacation villa and a city apartment is more than a real estate decision—it’s a lifestyle choice with financial, emotional, and environmental trade-offs. While a villa promises privacy and a slice of nature, an apartment delivers convenience and community. This guide breaks down the key differences to help you decide which path aligns with your priorities.

    The Money Question: What Does Each Home Really Cost?

    When comparing costs, it’s easy to focus on the purchase price alone. But the true financial picture includes ongoing expenses like maintenance, taxes, and utilities.

    Purchase price: Vacation villas typically cost between $1,500 and $4,000 per square meter in rural or coastal areas, while city apartments range from $3,000 to $12,000 or more in prime urban locations. This means you can often afford a larger villa for the same price as a smaller apartment in a city center.

    Rent and income: City apartments offer stable rental income, with a 2-bedroom fetching $1,800 to $5,000 per month. Vacation villas have higher variability—$1,200 to $3,500 monthly—but can command premium rates during tourist season. If you’re investing, villa yields in hotspots can reach 5-8% gross, whereas city apartments typically yield 3-5% but appreciate more reliably.

    Maintenance and hidden fees: A villa’s annual upkeep runs 1.5-3% of its value, covering the roof, pool, and landscaping. Apartments are cheaper to maintain at 0.8-1.5% because costs are shared through HOA or strata fees. However, beware of special levies: strata fees can rise unexpectedly for major repairs.

    Lifestyle: Privacy vs. Convenience

    The everyday experience of living in a villa differs dramatically from an apartment.

    Villa life: You get a standalone structure with private outdoor space—a garden, pool, or terrace. This is ideal for families with children who need room to play, or for those who crave autonomy and quiet. But isolation can be a downside: you’re often far from services, and maintenance is entirely on you. A broken water heater? You’re calling the plumber. A fallen tree? You’re hauling it away.

    Apartment living: Convenience is the hallmark. You’re steps away from cafes, grocery stores, and public transit. Many buildings offer amenities like a gym, doorman, and shared green spaces. You also gain a community—neighbors who can water your plants or watch your flat. Yet, you trade privacy for that convenience: shared walls mean noise, and HOA rules can restrict everything from pet ownership to balcony decorations.

    Environmental Impact: Which Footprint Is Smaller?

    Sustainability is a growing concern, and the two home types have very different profiles.

    Villas tend to have a larger carbon footprint per person. Heating and cooling a larger, standalone structure consumes more energy, and a pool adds significant water and power use. Landscaping often requires irrigation and chemical treatments. However, villas offer more potential for eco-upgrades: solar panels, rainwater harvesting, and native gardens can significantly offset their impact.

    Apartments are more energy-efficient per square meter because shared walls reduce heat loss, and district heating is common. High-rise construction does have high embodied carbon, and urban heat island effects make cities warmer. But the concentration of people in a small footprint means fewer resources per person overall.

    Legal and Regulatory Hurdles: What You Can and Can’t Do

    Owning a home also means navigating local laws, and villas and apartments face different constraints.

    Zoning and ownership: Villas are typically freehold, meaning you own the land and the structure outright. Apartments are often leasehold or strata-titled, where you own your unit but share ownership of common areas. This affects what you can modify and how decisions are made.

    Short-term rentals: If you plan to rent out your property on Airbnb, beware: many cities restrict short-term rentals for apartments. NYC, Barcelona, and Tokyo have strict regulations or outright bans. Vacation villas in tourist zones usually face fewer restrictions, though you’ll still need a license.

    Which Is Right for You? A Practical Guide

    Your decision hinges on your life stage, work style, and goals.

    • Choose a villa if: You value space and privacy, work remotely and can live anywhere, or want to host family gatherings. You’re prepared for maintenance responsibilities and can handle seasonal income if you’re renting it out.
    • Choose an apartment if: You thrive on city energy, need access to cultural amenities, or want a low-maintenance lifestyle. You’re a first-time buyer or prefer a stable investment with predictable rental demand.

    Remember: you don’t have to pick one forever. Many people start with an apartment for convenience, then transition to a villa for retirement. Others buy a villa as a vacation rental, then move in later. The best choice is the one that matches your current life—not a lifelong commitment.

    Ultimately, the villa-versus-apartment debate isn’t about which is objectively better—it’s about which fits your personal and financial circumstances. By weighing the costs, lifestyle, environmental impact, and legal factors, you can make an informed choice that brings you joy and security. Whether that’s a sun-drenched villa or a sleek city flat, the right home is one that aligns with your values and goals.

    Summary

    • Cost: Villas have lower purchase prices per m² but higher maintenance and utilities; apartments cost more upfront but are cheaper to run.
    • Rental yields: Villas can yield 5-8% in tourist areas but with seasonal volatility; apartments yield 3-5% with stable demand.
    • Lifestyle: Villas offer privacy and outdoor space; apartments provide convenience and community.
    • Environmental impact: Villas have larger footprints but more potential for eco-upgrades; apartments are more efficient per m².
    • Regulations: Short-term rentals are often restricted for apartments; villas in tourist zones face fewer hurdles.

    FAQ

    Q: Is a villa or apartment a better investment?
    A: It depends on your goals. If you seek high rental yields and are willing to handle seasonality and maintenance, a villa in a tourist hotspot can be lucrative. If you prefer stability and lower hassle, an apartment in a city offers consistent rental demand and easier financing.

    Q: Can I rent out my apartment on Airbnb?
    A: Many cities like New York, Barcelona, and Tokyo restrict or ban short-term rentals for apartments. Check local laws and your building’s HOA rules before listing your unit.

    Q: What are the hidden costs of owning a villa?
    A: Beyond maintenance (1.5-3% of value annually), villas often have higher insurance premiums due to weather exposure and liability, plus higher utility bills for heating, cooling, and pool upkeep.

    Q: Are apartments more environmentally friendly than villas?
    A: Generally, yes—apartments are more energy-efficient per square meter due to shared walls and district heating. However, villas can install solar panels and rainwater systems to reduce their impact.

    Q: Which is better for a family with children?
    A: A villa is often ideal for families, offering outdoor play space and room for multi-generational stays. But consider proximity to schools and the commute if you work in a city—an apartment might be more practical.
  • Beachfront vs. City Center: Weighing Ocean Views Against Urban Convenience

    Inside Global Convenience: A Conversation with the Artists | Waterfront Toronto

    Choosing between a beachfront and a city center home is more than picking a view. It’s a decision about how you want to live each day. The beach offers the sound of waves and a resort-like atmosphere, while the city buzzes with career prospects and cultural energy. The right choice depends on your priorities, finances, and lifestyle.

    This isn’t just about personal taste; it’s a financial and practical trade-off. Beachfront properties often cost 30–100% more per square foot than comparable city-center homes, yet they offer scarcity-driven appreciation and vacation rental potential. City centers, on the other hand, provide shorter commutes and year-round rental demand. Understanding these differences can help you make a choice you won’t regret.

    The Numbers: Cost and Investment

    When it comes to price, beachfront living is a premium game. In the same metro area, beachfront properties can fetch 30–100% more per square foot than city-center equivalents. That premium reflects the limited supply of coastline and the high demand for ocean views. But the costs don’t stop at the purchase price. Insurance for beachfront homes often runs 2–5 times higher due to flood, wind, and storm surge risks. In some coastal areas, insurers have even pulled out, making coverage harder to find.

    City-center living might be more affordable upfront, but it comes with its own expenses. Condo and HOA fees can be steep, especially in newer high-rises. However, these fees often cover amenities like gyms, pools, and security, which can offset some costs. Appreciation rates vary too. Beachfront properties have historically shown strong long-term appreciation because the coastline can’t expand, but city centers can appreciate faster in emerging urban markets—though with more volatility.

    Rental Income: Seasonal Spikes vs. Steady Occupancy

    If you’re thinking about renting out your property, the dynamics differ sharply. Beachfront properties can command 2–3 times higher nightly rates on platforms like Airbnb and VRBO. A beachfront condo might rent for $300 a night in peak season, while a similar city-center unit goes for $150. But beachfront occupancy is seasonal—you’ll have packed summers and empty winters in many markets. City-center rentals, especially near business districts, enjoy steadier year-round occupancy. Office workers and students need housing all year, not just in July.

    For investors, the choice depends on your risk tolerance. Beachfront offers high rewards during peak season but requires managing vacancies. City-center provides predictable cash flow but with lower per-night returns.

    Lifestyle: Waves vs. City Lights

    The lifestyle differences are stark. Beachfront living means waking up to ocean views, stepping onto the sand, and hearing waves instead of traffic. It’s quieter, with more privacy and natural light. But daily amenities are limited—you’ll likely need to drive 10–20 minutes for groceries, restaurants, or healthcare. Commutes to work can stretch 30–60 minutes each way.

    City-center living puts you in the heart of the action. Walk to work, grab dinner at a new bistro, or catch a show. Public transit and bike lanes make car ownership optional. The downside? Noise from traffic, sirens, and nightlife, plus less personal space. If you thrive on social energy and cultural events, the city has the edge. If you crave tranquility and outdoor activity, the beach wins.

    The Remote Work Shift

    The pandemic upended the calculus. With remote work, many people flocked to beachfront towns, driving up prices in places like Sarasota, FL, and San Clemente, CA. But as companies push return-to-office, some demand has swung back. Hybrid work schedules have permanently expanded the viable radius—you can live by the beach and commute a few days a week.

    Remote workers often find beachfront ideal if they have stable income and can handle the isolation. Coworking spaces are growing in coastal towns, but they’re still limited. City centers offer better internet infrastructure and networking opportunities, plus backup employment options if your job situation changes.

    Family Considerations: Schools and Services

    Families face a different set of trade-offs. Beachfront towns often have weaker school districts—they’re tourist economies, not education hubs. Pediatric services may be limited, and extracurricular activities might require long drives. City centers typically offer better schools, hospitals, and childcare options. But urban living often means smaller apartments and less outdoor space for kids to play.

    If you have school-age children, the city center likely wins on practical grounds. For retirees or childless couples, the beach’s serenity might outweigh the lack of services.

    Climate Risk and Future Values

    Climate change is reshaping beachfront markets. Rising sea levels and stronger storms are beginning to discount values in high-risk zones, especially Florida’s Atlantic and Gulf coasts. Some buyers are pivoting to ‘coastal-adjacent’ inland areas that offer proximity to the beach without the flood risk. Meanwhile, city centers face less climate risk but are more vulnerable to economic downturns.

    Insurance costs are a key indicator—if insurers are fleeing, that’s a red flag. Always check flood maps and talk to local agents before buying beachfront.

    Which One Is Right for You?

    There’s no universal answer. Beachfront is perfect for those who value wellness, privacy, and a slower pace. The mental health benefits of ocean proximity are real—reduced stress, better sleep. But you must be comfortable with longer drives and seasonal crowds.

    City center suits career-driven professionals, families, and anyone who thrives on convenience. The walkability and cultural access are unbeatable, and the steady rental market provides financial stability. But you’ll trade natural scenery for urban noise.

    Consider your work situation, family needs, and how you want to spend your weekends. If you’re torn, try renting in each location for a few months. Experience beats speculation.

    Choosing between beachfront and city center is a deeply personal decision. The numbers can guide you, but your lifestyle will ultimately decide. Weigh the costs, the commute, the schools, and the view. The right choice is the one that makes you feel at home—whether that’s to the sound of waves or the hum of the city.

    Summary

    • Beachfront properties cost 30–100% more per square foot and have 2–5x higher insurance, but offer scarcity-driven appreciation and high seasonal rental income.
    • City center living provides shorter commutes, year-round rental demand, and access to amenities, but often with higher HOA fees and less natural scenery.
    • Beachfront offers wellness benefits like reduced stress and better sleep, but may lack quality schools and healthcare in tourist towns.
    • Remote work has expanded the feasibility of beachfront living, but city centers still offer better infrastructure and employment backup.
    • Climate change is beginning to impact beachfront values, particularly in high-risk coastal zones.

    FAQ

    Q: Is beachfront living a good investment?
    A: Yes, if you can handle the higher upfront costs and insurance. Beachfront properties have historically appreciated well due to limited supply. However, consider climate risks and seasonal rental fluctuations.

    Q: Are city center rentals more profitable than beachfront?
    A: City center rentals typically offer steadier occupancy, especially in business districts, but lower nightly rates. Beachfront can yield 2–3x higher nightly rates but only during peak season.

    Q: Which is better for families?
    A: City center usually wins for families due to better schools, healthcare, and childcare options. Beachfront towns often have weaker school districts and fewer services.

    Q: How does remote work affect the choice?
    A: Remote work makes beachfront living more feasible, as you don’t need to commute daily. However, city centers still offer better internet infrastructure and networking opportunities.

    Q: What are the risks of beachfront properties?
    A: Higher insurance costs, climate change risks like sea-level rise and storms, and potential for seasonal business downturns in tourist-dependent areas.

  • 5 Home Upgrades That Pay for Themselves in Resale Value

    5 Home Upgrades That Pay for Themselves in Resale Value

    When you sell your home, not all renovations are created equal. Some upgrades, like a new front door, can recoup nearly 100% of their cost, while others, like a luxury kitchen remodel, might only bring back half of what you spent. The difference often comes down to choosing projects that buyers universally value and that fit your neighborhood’s price ceiling.

    This guide breaks down the five upgrades that consistently offer the best return on investment (ROI), based on data from Remodeling Magazine’s annual Cost vs. Value Report. We’ll also bust common myths and show you how to avoid the renovation trap that leaves sellers over-improved and under-compensated.

    Why Resale Value Matters

    In a hot seller’s market, buyers may overlook dated kitchens or worn carpets. But in a buyer’s market, strategic upgrades can set your listing apart. The key is to focus on improvements that add genuine value, not just personal enjoyment. According to real estate agents, curb appeal is the #1 driver of showings and offers. A fresh front door or new siding can make a buyer’s first impression positive, and that’s often half the battle.

    However, appraisers don’t care what you spent. They compare your home to similar sales in the area. If your $50,000 kitchen remodel exceeds the standard in your neighborhood, you might only recoup $20,000. The golden rule in real estate: avoid being the most expensive house on the block. Upgrades should match your local market’s expectations, not exceed them.

    The Top 5 Upgrades for Resale Value

    1. Entry Door Replacement (Steel)

    A steel entry door is the single most cost-effective upgrade you can make. With an average cost of $2,300, you can recoup up to 100% of that investment at resale. This isn’t just about aesthetics—a sturdy door improves security and energy efficiency, both of which appeal to buyers. Choose a neutral color and classic design to maximize appeal.

    2. Garage Door Replacement

    A new garage door can recoup 93–97% of its $4,000 cost. It’s a major component of your home’s facade, so replacing a worn or dated garage door instantly boosts curb appeal. Opt for a style that complements your home’s architecture, and consider insulation for added energy savings.

    3. Minor Kitchen Remodel (Mid-Range)

    You don’t need a full gut renovation to see returns. A minor kitchen remodel—think refacing cabinets, replacing countertops, and updating appliances—costs about $27,000 on average and recoups 70–85% at resale. Focus on cosmetic updates that make the space feel fresh and modern, without over-improving beyond your neighborhood’s standard.

    4. Siding Replacement (Fiber-Cement)

    Replacing old siding with fiber-cement material costs around $17,000 and recoups 70–80%. Beyond aesthetics, new siding improves insulation, which is a selling point for energy-conscious buyers. It also reduces maintenance, a major appeal for buyers seeking a move-in-ready home.

    5. Attic Insulation (Fiberglass)

    This is the rare upgrade that can literally pay for itself. With an average cost of $1,500–$3,000, attic insulation can recoup over 100% of its cost through utility savings alone. Plus, it’s a selling point in colder climates, where buyers prioritize energy efficiency. It’s a small investment with a big payoff in both comfort and resale value.

    The Caveat: ‘Pay for Themselves’ Is a Loose Term

    Only doors and insulation come close to breaking even. Most upgrades recoup 60–100% of their cost. The rest ‘pay for themselves’ when you combine resale value with the enjoyment and energy savings you get while living in the home. Don’t expect a dollar-for-dollar return on any renovation—instead, view it as a way to make your home more competitive and enjoyable.

    Myths About Home Upgrades

    Myth: All Kitchen Remodels Pay Off

    False. High-end kitchen remodels often recoup only 50–60%. Minor, cosmetic updates have better ROI. Stick to simple changes that brighten the space, like new hardware, refaced cabinets, and modern appliances.

    Myth: More Spending Equals More Return

    False. ROI diminishes as project cost increases. A $10,000 kitchen refresh may return 90%, while an $80,000 luxury remodel may return only 55%. Be mindful of your budget and your neighborhood’s value ceiling.

    Myth: Swimming Pools Add Value

    Generally false in most climates. Pools are a liability for many buyers due to safety concerns, maintenance, and insurance costs. In cooler regions, they can even reduce offers.

    Myth: Home Offices Are a Must-Have

    Partially true. A dedicated office adds value, but converting a bedroom into an office can drop your bedroom count, which reduces value. Keep a flexible space that can serve both purposes.

    Myth: Energy-Efficient Upgrades Always Pay Off

    Not always. Solar panels can be a turn-off if leased, as buyers don’t want to assume contracts. Insulation and efficient windows are safer bets because they offer immediate savings.

    The Bottom Line

    Focus on small-ticket, high-impact items like doors, siding, and insulation. Avoid over-improving for your neighborhood, and consider DIY for labor-intensive tasks to boost ROI. Most importantly, understand that resale value is about appealing to the broadest pool of buyers, not just your personal taste. Neutral, well-maintained upgrades will serve you best when it’s time to sell.

    Choosing the right upgrades can make your home more attractive to buyers without breaking the bank. Prioritize curb appeal, avoid over-improvement, and consider the long-term savings of energy-efficient projects. Remember, the goal is not to recoup every dollar but to make your home stand out in a competitive market.

    Summary

    • Steel entry door replacement offers the highest ROI, recouping up to 100% of its cost.
    • Garage door replacement recoups 93–97%, making it a curb appeal winner.
    • Minor kitchen remodels (not full gut renovations) recoup 70–85%.
    • Fiber-cement siding boosts curb appeal and energy efficiency, recouping 70–80%.
    • Attic insulation can pay for itself through utility savings alone, often recouping over 100%.

    FAQ

    Q: What is the single best upgrade for resale value?
    A: A steel entry door replacement, which recoups up to 100% of its cost on average.

    Q: Do I need to renovate my kitchen to sell?
    A: No. A minor kitchen remodel (e.g., refacing cabinets, updating appliances) offers better ROI than a full renovation.

    Q: Will a pool increase my home’s value?
    A: Generally no. In most climates, pools are a liability and can even reduce offers due to maintenance and safety concerns.

    Q: Are energy-efficient upgrades worth it?
    A: Yes, especially insulation and efficient windows, which provide immediate savings and appeal to buyers. Solar panels may not always pay off if leased.

    Q: How do I avoid over-improving my home?
    A: Research comparable sales in your neighborhood and keep upgrades in line with the median home’s features. Don’t be the most expensive house on the block.

  • The Ultimate Home Buying Checklist: Your Step-by-Step Guide to a Smooth Purchase

    The Ultimate Home Buying Checklist: Your Step-by-Step Guide to a Smooth Purchase

    Buying a home is one of the biggest financial decisions you’ll ever make—and it can feel overwhelming. With mortgage rates hovering around 6–7% and inventory tight in many markets, there’s little room for error. A single misstep—like skipping a home inspection or underestimating closing costs—can cost you thousands.

    That’s where a solid checklist comes in. It keeps you organized, disciplined, and focused on what matters, from your first credit check to the final walkthrough. Whether you’re a first-time buyer or a seasoned pro, this guide breaks down every phase of the home buying process into clear, actionable steps.

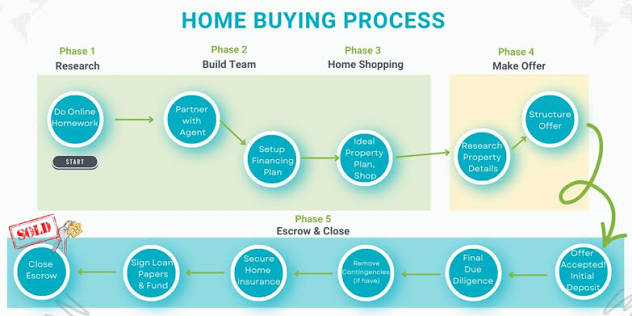
    Phase 1: Pre-Purchase Preparation (2–3 Months Before)

    Before you even start browsing listings, you need to get your financial house in order. This phase is all about building a strong foundation.

    Check Your Credit Report

    Your credit score directly impacts your mortgage rate and loan approval. Pull your credit report from all three bureaus (Equifax, Experian, TransUnion) and review for errors. Dispute any inaccuracies—this can boost your score. For FHA loans, a minimum score of 580 is typically required (with a 3.5% down payment), while conventional loans usually need at least 620. Higher scores unlock better rates, so if your score is below 700, consider spending a few months improving it.

    Save for Down Payment and Closing Costs

    Conventional loans typically require 3–20% down, but FHA allows as low as 3.5%, and VA/USDA loans can go as low as 0%. Don’t forget closing costs—they typically run 2–5% of the purchase price, covering appraisal, title search, attorney fees, loan origination, and prepaid taxes/insurance. Aim to have both saved before you start house hunting.

    Get Pre-Approved

    A pre-approval letter from a lender shows sellers you’re serious and tells you exactly how much you can borrow. You’ll need to provide photo ID, pay stubs (last 30 days), W-2s (last 2 years), bank statements (last 2–3 months), tax returns, and proof of assets. This step also helps you set a realistic budget—remember, your debt-to-income (DTI) ratio should ideally be below 43–50%.

    Define Your Must-Haves vs. Nice-to-Haves

    Make a list of non-negotiables (e.g., number of bedrooms, location, school district) and nice-to-haves (e.g., a pool, updated kitchen). This will keep you focused during house hunting and prevent you from falling in love with a house that doesn’t meet your core needs.

    Phase 2: House Hunting (1–3 Months)

    Now the fun part—but stay disciplined. Use your checklist to evaluate each property objectively.

    Research Neighborhoods

    Don’t just look at the house; look at the block. Check commute times, walkability, proximity to family, and future development plans. If you have kids, verify school ratings—even if you don’t, good schools boost resale value. Visit at different times of day to gauge noise and traffic.

    Attend Open Houses and Private Showings

    Take photos, notes, and measurements. Compare each home against your must-have list. Don’t be swayed by staging—look past the decor to the bones of the house.

    Review HOA Rules

    If the home is in a homeowners association (HOA), get a copy of the covenants, conditions, and restrictions (CC&Rs) before making an offer. HOA fees can add hundreds to your monthly costs, and rules may restrict everything from paint colors to parking.

    Phase 3: Making an Offer and Negotiating (1–2 Weeks)

    Once you find the right home, it’s time to act—but with a clear strategy.

    Compare Comps

    Your real estate agent can pull comparable sales (comps) to help you decide a fair offer price. In a hot market with bidding wars, you may need to offer over asking; in a slow market, you might negotiate below. Know your walk-away number in advance—don’t get caught in a bidding frenzy.

    Include Contingencies

    Protect yourself with contingencies: inspection, financing, and appraisal. These allow you to back out without losing your earnest money if something goes wrong.

    Review Seller Disclosures

    Sellers are required to disclose known issues. Read these carefully—they can reveal problems like roof leaks, foundation cracks, or past pest infestations.

    Phase 4: Home Inspection and Appraisal (2–4 Weeks)

    This is where you uncover hidden problems and confirm the home’s value.

    Hire a Licensed Inspector

    You hire and pay the inspector (typically $300–$500). Attend the inspection—it’s a learning opportunity. The inspector will check structural integrity, roof, HVAC, plumbing, electrical, and more. If issues arise, you can request repairs or credits, or walk away if they’re deal-breakers.

    Appraisal

    Your lender orders an appraisal to ensure the home is worth the loan amount. If the appraisal comes in low, you may need to renegotiate the price or bring more cash to closing.

    Phase 5: Final Loan Approval and Closing (2–4 Weeks)

    You’re almost there—but don’t let your guard down.

    Lock Your Interest Rate

    Rates can fluctuate, so lock in your rate when you’re comfortable. Your lender will guide you through final loan terms.

    Review the Closing Disclosure

    Three days before closing, you’ll receive a Closing Disclosure detailing all final costs. Review it carefully against your loan estimate—any discrepancies should be addressed immediately.

    Final Walkthrough

    Do a final walkthrough 24 hours before closing to ensure the home is in the agreed-upon condition and any requested repairs were made.

    Closing Day

    Bring certified funds (cashier’s check or wire transfer) for your down payment and closing costs. You’ll sign a mountain of paperwork, but your agent and title company will guide you. After signing, you’ll receive the keys—congratulations, you’re a homeowner!

    Hidden Costs to Budget For

    Beyond the purchase price, plan for:
    Property taxes and insurance (often escrowed into your monthly payment)
    Maintenance: 1–3% of home value annually
    Utilities (may be higher than renting)
    HOA fees (if applicable)
    Moving expenses and immediate repairs or furnishings

    Avoid being “house poor”—spend no more than 30% of your gross income on housing. A checklist isn’t just about the steps; it’s about staying financially healthy for the long haul.

    Buying a home is a marathon, not a sprint. With the right checklist, you can navigate each phase with confidence—from pre-approval to closing day. Remember, the goal isn’t just to buy a house; it’s to find a home that fits your life and your budget. Use this guide as your roadmap, and you’ll be well-prepared to make one of the biggest investments of your life.

    Summary

    • Start with financial prep: Check your credit, save for down payment and closing costs, and get pre-approved.
    • Define your must-haves before house hunting to stay focused.
    • Always include contingencies (inspection, financing, appraisal) in your offer.
    • Budget for hidden costs like maintenance, taxes, and HOA fees.
    • Review the Closing Disclosure and do a final walkthrough before signing.

    FAQ

    Q: How long does the home buying process take?
    A: Typically 3–6 months from start to finish. Cash buyers can close in as little as 2–3 weeks, but financed purchases take longer due to appraisal and underwriting.

    Q: What credit score do I need to buy a home?
    A: For FHA loans, a minimum of 580 (with 3.5% down) is typical. Conventional loans usually require at least 620. Higher scores get better rates.

    Q: How much should I save for closing costs?
    A: Closing costs typically run 2–5% of the purchase price, covering appraisal, title search, attorney fees, loan origination, and prepaid taxes/insurance.

    Q: What is a debt-to-income ratio and why does it matter?
    A: DTI is your monthly debt payments divided by your gross monthly income. Most lenders cap DTI at 43–50%, with housing costs alone ideally under 28–31%.

    Q: Can I skip the home inspection to save money?
    A: No. An inspection (typically $300–$500) can uncover costly issues like structural problems or roof damage. It’s a small price for peace of mind and negotiating power.

  • 6 Secrets Real Estate Agents Don’t Tell Buyers (But You Need to Know)

    6 Secrets Real Estate Agents Don’t Tell Buyers (But You Need to Know)

    Buying a home is one of the biggest financial decisions you’ll ever make, yet most buyers walk into the process with a dangerous blind spot: they assume their real estate agent is working purely in their best interest. The truth is, the industry is structured in ways that can quietly work against you—unless you know what to look for.

    From hidden commission negotiations to off-market listings, there are several things agents rarely volunteer to buyers. Some of these are legal gray areas, others are just industry norms that favor the seller. But all of them can cost you money or leave you with a home that isn’t what you expected.

    Here are six secrets that real estate agents often keep from buyers—and how you can use this knowledge to your advantage.

    1. Your Agent’s Commission Is Negotiable—and You Can Ask for a Rebate

    Most buyers assume the commission their agent earns is a fixed, non-negotiable fee. In reality, buyer’s agents typically earn 2.5–3% of the purchase price, but this is not set by law. In traditional transactions, the seller pays the commission (split between the listing agent and the buyer’s agent), but that doesn’t mean you have no say.

    In many states, you can negotiate a lower commission with your agent before you sign a representation agreement. You can also ask for a rebate—a portion of the commission returned to you at closing. Rebates are legal in most states (though some prohibit them), and they can save you thousands of dollars.

    What to do: When interviewing agents, ask about their commission structure upfront. Don’t be afraid to negotiate or ask for a rebate. If an agent refuses, consider working with a discount brokerage or flat-fee service.

    2. The MLS Isn’t the Whole Market—Pocket Listings Exist

    The Multiple Listing Service (MLS) is the database agents use to share listings, but it’s not the only place homes are sold. An estimated 10–20% of homes in some markets are sold off-market or as pocket listings—never appearing on the MLS.

    Sellers choose pocket listings for various reasons: they want privacy, they’re testing the market, or they want to avoid the hassle of public showings. For buyers, this means you might miss out on the perfect home if your agent doesn’t have access to these off-market networks.

    What to do: Ask your agent if they have access to pocket listings or off-market properties. Some agents have exclusive relationships with sellers who prefer privacy. If your agent says no, consider working with a well-connected agent who has a strong network.

    3. Dual Agency: One Agent, Two Masters—and a Conflict of Interest

    In many states, a single agent can represent both the buyer and the seller in the same transaction. This is called dual agency, and it creates an inherent conflict of interest. The agent owes fiduciary duties—loyalty, confidentiality, and full disclosure—to both parties simultaneously, which is impossible to do fully.

    For example, if you tell the agent your maximum budget is $500,000, they are legally obligated to keep that confidential from the seller. But as a dual agent, they also have a duty to get the best price for the seller. This puts them in an impossible position, and it’s often the buyer who loses out.

    What to do: Ask your agent if they are willing to act as a dual agent. If they say yes, be cautious. In some states, dual agency is prohibited entirely, but in others, it’s allowed with written consent. If you’re uncomfortable, insist on working with an agent who represents only you.

    4. Home Inspections Are Not Pass/Fail—Everything Is Negotiable

    Many buyers treat the home inspection report as a checklist of deal-breakers. But the truth is, an inspection report lists defects, and almost everything is negotiable. Sellers routinely refuse to fix minor issues, and buyers often overestimate what is “unacceptable.”

    For example, a cracked window or a worn-out water heater might seem like major issues, but they’re often easy to fix or can be negotiated into a lower price. On the other hand, major structural problems—like foundation issues or a leaking roof—might be deal-breakers, but even those can be negotiated with a price reduction or seller credit.

    What to do: Don’t walk away from a home just because the inspection report has a long list of issues. Instead, prioritize the items: separate deal-breakers from minor repairs. Use the report as a negotiating tool to ask for a price reduction or repairs.

    5. List Price Is a Marketing Tool, Not a Valuation

    Sellers (with their agent’s guidance) often price homes strategically—not based on what the home is worth, but based on what will attract buyers. Some price below market value to spark a bidding war, while others price above market value to leave room for negotiation. The list price has no legal or appraisal significance.

    This means you shouldn’t assume a home priced below market is a bargain, or that one priced above market is overpriced. Instead, look at comparable sales (comps) to determine the home’s true value.

    What to do: Ask your agent for a comparative market analysis (CMA) before making an offer. Look at recent sales of similar homes in the area to get a sense of fair market value. Don’t be swayed by the list price alone.

    6. Appraisals Can Be Challenged—Don’t Take a Low Appraisal as Final

    If the home you’re buying appraises for less than your offer price, you might think you’re stuck. But that’s not true. Appraisals are not infallible, and you can challenge a low appraisal by requesting a reconsideration of value (ROV).

    An ROV is a formal request to the appraiser to review additional comparable sales data that might support a higher value. Your agent can help you gather comps and submit an ROV. If the appraiser agrees, the value can be adjusted, saving your deal.

    What to do: If your appraisal comes in low, don’t panic. Ask your agent to help you prepare an ROV with recent comparable sales that were not considered. This can be a powerful tool to keep your purchase on track.

    The real estate industry is full of nuances that can work against buyers who aren’t in the know. But with these six secrets, you’re now equipped to ask the right questions, negotiate better, and avoid costly mistakes. Remember, your agent works for you—but only if you make them accountable. So go in prepared, and you’ll be one step ahead in the game of buying a home.

    Summary

    • Commission is negotiable: You can ask for a lower fee or a rebate in many states.
    • Pocket listings exist: 10–20% of homes are sold off-market, so ask your agent about them.
    • Dual agency creates conflicts: One agent representing both sides can’t fully protect your interests.
    • Inspection issues are negotiable: Not every defect is a deal-breaker; use the report to negotiate.
    • List price is a strategy: It’s not a true valuation, so rely on comps instead.
    • Low appraisals can be challenged: An ROV can help you get a fair value.

    FAQ

    Q: Can I really negotiate my buyer’s agent’s commission?
    A: Yes, in most cases. The commission is not set by law, and you can discuss it with your agent before signing a representation agreement. Some agents may be willing to lower their fee or offer a rebate to win your business.

    Q: What is a pocket listing, and how can I access them?
    A: A pocket listing is a home that is sold without being listed on the MLS. They are often marketed through private networks. Ask your agent if they have access to off-market properties, or consider working with an agent who specializes in exclusive listings.

    Q: Is dual agency legal?
    A: It depends on the state. Some states prohibit it, while others allow it with written consent from both parties. Even where legal, it creates a conflict of interest, so it’s best to avoid it if possible.

    Q: What should I do if the inspection report shows major issues?
    A: Don’t automatically walk away. Use the report to negotiate a lower price or request repairs. For major issues, you can also ask for a credit at closing to cover the cost of repairs.

    Q: How can I challenge a low appraisal?
    A: You can request a reconsideration of value (ROV) by providing the appraiser with additional comparable sales that support a higher value. Your agent can help you gather this data and submit the request.

  • How Technology Is Changing the Rent vs. Buy Decision

    How Technology Is Changing the Rent vs. Buy Decision

    For decades, the choice between renting and buying a home was a straightforward financial calculation, often distilled into a simple rule of thumb: if you plan to stay put for at least five years, buying is the better investment. But the landscape has shifted dramatically. With mortgage rates hovering near 7%, home prices at record highs, and a new generation of digital tools reshaping everything from how we search for homes to how we build credit, the decision is no longer just about numbers—it’s about navigating a complex ecosystem of technology, data, and evolving lifestyles.

    This article explores how fintech, proptech, and AI are transforming the rent vs. buy equation. We’ll look at the traditional financial metrics, the new digital tools that are changing the game, and the broader implications for wealth-building and flexibility. Whether you’re a first-time buyer, a long-term renter, or someone just curious about the future of housing, understanding these technological shifts is essential to making an informed choice.

    The Traditional Financial Framework

    Before diving into the tech, it’s helpful to understand the classic metrics used to compare renting and buying. These are the tools that financial advisors and online calculators have used for years.

    Price-to-Rent Ratio

    This is a simple metric: divide the price of a home by the annual rent for a comparable property. For example, if a home costs $300,000 and would rent for $1,500 per month ($18,000 per year), the price-to-rent ratio is 300,000 / 18,000 = 16.7. A ratio below 15–20 generally suggests that buying is financially favorable, while a higher ratio indicates renting might be the smarter choice. This ratio gives a quick snapshot of whether a market is buyer-friendly or renter-friendly.

    The 5% Rule

    Another rule of thumb is the 5% rule, which compares the annual cost of owning a home to the annual cost of renting. The annual cost of owning includes:

    • Maintenance: about 1% of the home’s value
    • Property taxes: 1–2%
    • Insurance: about 0.5%
    • Opportunity cost of the down payment: if you put 20% down, that money could be invested elsewhere, potentially earning 3–4% annually

    Add these up, and you get roughly 5–7% of the home’s value per year. If that total is less than what you’d pay in rent for a similar property, buying may be the better deal. For example, if you own a $300,000 home, the annual cost of ownership might be around $15,000–$21,000. If you could rent the same home for $1,500 per month ($18,000 per year), it’s a close call.

    Breakeven Horizon

    This is the number of years you need to stay in a home for buying to become more cost-effective than renting. It accounts for upfront costs (down payment, closing costs) and ongoing costs (mortgage, taxes, maintenance) versus rent, and factors in appreciation. Historically, the breakeven horizon has been 5–7 years, but it varies widely by market and interest rates. With today’s high rates, the breakeven point has stretched longer in many areas.

    The Tech Revolution in Real Estate

    Now, let’s look at how technology is disrupting this traditional framework. The rise of proptech (property technology) and fintech (financial technology) has introduced new tools that change the way we evaluate and execute the rent vs. buy decision.

    Proptech: Smarter Home Search and Data

    Platforms like Zillow, Redfin, and Compass have transformed home search. Instead of relying on a real estate agent to show you listings, you can now:

    • Access real-time data: See historical price trends, neighborhood statistics, and school ratings.
    • Take virtual tours: 3D walkthroughs and video tours let you explore homes from anywhere.
    • Use predictive analytics: AI tools can estimate future home appreciation and rental price trends, helping you make a more informed guess about the future.

    For example, Zillow’s ‘Zestimate’ uses machine learning to estimate home values, and while it’s not perfect, it provides a data-driven starting point. Redfin offers ‘Redfin Estimate’ and also provides tools to compare the cost of buying vs. renting in a specific area.

    Fintech: Digital Mortgages and Alternative Credit

    Getting a mortgage used to involve piles of paperwork and weeks of waiting. Now, digital lenders like Better.com, Rocket Mortgage, and SoFi offer:

    • Online pre-approval: Get pre-approved in minutes, not days.
    • Automated underwriting: AI algorithms can assess your financial profile faster and sometimes more accurately than human underwriters.
    • Lower down payment options: Some fintechs offer loans with as little as 3% down, and some even offer zero-down options for qualified buyers.

    But perhaps the most significant fintech innovation is the use of alternative data in credit scoring. Traditional credit scores often exclude rent payments, which can hurt renters who are financially responsible but have limited credit history. Now, services like Experian Boost and RentTrack allow renters to report their on-time rent payments to credit bureaus, helping them build credit without a mortgage. This narrows the historical advantage of homeownership for credit building.

    RentTech: Streamlining the Rental Experience

    Renting has also gone digital. Platforms like Zumper and Apartments.com offer:

    • Online applications: Apply for apartments entirely online.
    • Digital lease signing: E-sign your lease without meeting the landlord in person.
    • Security deposit alternatives: Companies like Rhino offer insurance instead of a large upfront deposit, making renting more affordable.

    These tools make renting more convenient and flexible, which is particularly appealing to younger generations who value mobility.

    The Rise of ‘Buy Now, Rent Later’ and Fractional Ownership

    One of the most intriguing developments is the blurring of lines between renting and buying. Startups like Divvy Homes offer ‘rent-to-own’ programs where a portion of your rent goes toward a future down payment. Others like Pacaso and Arrived allow you to buy fractional shares of a property, so you can invest in real estate without buying a whole home. These models are still evolving, but they represent a new middle ground.

    The Impact of High Interest Rates and the Lock-In Effect

    As of late 2024, mortgage rates are around 6.5–7.5%, up from sub-3% in 2021. This has had a profound effect on the market. Many existing homeowners who locked in low rates are reluctant to sell and give up that cheap mortgage, a phenomenon known as the ‘lock-in effect.’ This has reduced the supply of homes for sale, keeping prices high even as demand cools.

    For potential buyers, this means the financial math is less favorable than it was a few years ago. The breakeven horizon has lengthened, and the price-to-rent ratio has risen in many metros. This is where technology can help: by using AI-powered calculators that incorporate current rates, taxes, and maintenance costs, you can get a more personalized and accurate picture.

    The Lifestyle and Flexibility Angle

    Beyond the numbers, technology has also changed the lifestyle calculus. The rise of remote work has made location flexibility more valuable. If you can work from anywhere, renting might be more appealing because it allows you to move easily to a new city or even a new country. Digital nomads, in particular, may find renting aligns better with their lifestyle.

    On the other hand, technology has also made homeownership more manageable. Smart home devices can monitor and automate maintenance, and apps can connect you with service providers. Some platforms even offer ‘home management’ services that handle repairs and upkeep for a fee, reducing the burden of ownership.

    The Wealth-Building and Generational Perspective

    Homeownership has long been a primary wealth-building tool, especially for middle-class families. However, historical discriminatory practices like redlining have created disparities in homeownership rates among different racial and ethnic groups. Fintech is attempting to address this by democratizing access:

    • Lower down payment options: Some lenders now offer 1% down programs.
    • Down payment assistance: Apps can help you find grants and assistance programs.
    • Rent reporting: As mentioned, this helps renters build credit.

    But critics argue that some of these innovations, like rent-to-own programs, can be predatory if not carefully regulated. It’s essential to read the fine print and understand the terms.

    Making the Decision: A Tech-Enabled Approach

    So, how do you decide? Here’s a step-by-step approach that leverages technology:

    1. Use a comprehensive rent vs. buy calculator: The New York Times, Zillow, and NerdWallet offer calculators that factor in your specific situation, including down payment, interest rate, and expected length of stay.
    2. Analyze market data: Use sites like Zillow and Redfin to see price trends and rental rates in your desired area.
    3. Check your credit score: Use free services like Credit Karma to see where you stand. If your score is low, consider using rent reporting to boost it.
    4. Explore financing options: Get pre-approved from multiple lenders, including online fintechs, to see what rates and terms you qualify for.
    5. Consider your lifestyle: Think about your career plans, family goals, and how much you value flexibility. Technology can help you work remotely, but it can’t make a decision for you.

    Remember, the decision is not just about money—it’s about your life. Technology provides data and tools, but the final choice is personal.

    The rent vs. buy decision has always been complex, but technology is making it more nuanced and more accessible. From AI-powered calculators that crunch the numbers to fintech innovations that lower barriers to entry, the tools we have today are powerful. However, they also require a new level of digital literacy. As you weigh your options, remember that the best choice depends on your financial situation, your lifestyle, and your long-term goals. Use the technology to inform your decision, but don’t let it make the decision for you.

    Summary

    • The traditional metrics (price-to-rent ratio, 5% rule, breakeven horizon) still provide a useful baseline, but they must be adapted to current high-interest-rate conditions.
    • Proptech platforms like Zillow and Redfin offer data-driven insights and predictive analytics that can help you evaluate markets.
    • Fintech innovations, including digital mortgages and rent reporting, are making homeownership more accessible and helping renters build credit.
    • RentTech tools streamline the rental process, making renting more convenient and flexible.
    • The ‘lock-in effect’ of low-rate mortgages is reducing housing inventory, keeping prices high, and making the buy decision less financially favorable in many areas.
    • Emerging models like rent-to-own and fractional ownership are blurring the lines between renting and buying, offering new options.

    FAQ

    Q: What is the price-to-rent ratio and how do I use it?
    A: The price-to-rent ratio is the home price divided by the annual rent for a comparable property. A ratio below 15–20 suggests buying is favorable, while above that, renting may be better. For example, a $300,000 home that rents for $1,500/month has a ratio of 16.7, which is borderline.

    Q: How does the 5% rule work?
    A: The 5% rule estimates the annual cost of owning as a percentage of the home’s value: 1% maintenance, 1–2% property taxes, 0.5% insurance, and 3–4% opportunity cost of the down payment. If this total (around 5–7%) is less than what you’d pay in annual rent, buying may be better.

    Q: What is the breakeven horizon?
    A: The breakeven horizon is the number of years you need to stay in a home for buying to become more cost-effective than renting. It accounts for upfront and ongoing costs. Historically 5–7 years, it’s longer now due to high interest rates.

    Q: How can technology help me decide?
    A: Use online calculators (NYT, Zillow, NerdWallet) that factor in your specifics. Use proptech sites for market data and predictive analytics. Get pre-approved from digital lenders to see your rate. Use rent reporting to build credit if you’re a renter.

    Q: What is the lock-in effect?
    A: The lock-in effect refers to homeowners with low mortgage rates (e.g., 3%) being reluctant to sell and give up that cheap financing, reducing housing supply and keeping prices high. This makes buying less affordable for new buyers.