Tag: Investment

  • Beachfront vs. City Center: Weighing Ocean Views Against Urban Convenience

    Inside Global Convenience: A Conversation with the Artists | Waterfront Toronto

    Choosing between a beachfront and a city center home is more than picking a view. It’s a decision about how you want to live each day. The beach offers the sound of waves and a resort-like atmosphere, while the city buzzes with career prospects and cultural energy. The right choice depends on your priorities, finances, and lifestyle.

    This isn’t just about personal taste; it’s a financial and practical trade-off. Beachfront properties often cost 30–100% more per square foot than comparable city-center homes, yet they offer scarcity-driven appreciation and vacation rental potential. City centers, on the other hand, provide shorter commutes and year-round rental demand. Understanding these differences can help you make a choice you won’t regret.

    The Numbers: Cost and Investment

    When it comes to price, beachfront living is a premium game. In the same metro area, beachfront properties can fetch 30–100% more per square foot than city-center equivalents. That premium reflects the limited supply of coastline and the high demand for ocean views. But the costs don’t stop at the purchase price. Insurance for beachfront homes often runs 2–5 times higher due to flood, wind, and storm surge risks. In some coastal areas, insurers have even pulled out, making coverage harder to find.

    City-center living might be more affordable upfront, but it comes with its own expenses. Condo and HOA fees can be steep, especially in newer high-rises. However, these fees often cover amenities like gyms, pools, and security, which can offset some costs. Appreciation rates vary too. Beachfront properties have historically shown strong long-term appreciation because the coastline can’t expand, but city centers can appreciate faster in emerging urban markets—though with more volatility.

    Rental Income: Seasonal Spikes vs. Steady Occupancy

    If you’re thinking about renting out your property, the dynamics differ sharply. Beachfront properties can command 2–3 times higher nightly rates on platforms like Airbnb and VRBO. A beachfront condo might rent for $300 a night in peak season, while a similar city-center unit goes for $150. But beachfront occupancy is seasonal—you’ll have packed summers and empty winters in many markets. City-center rentals, especially near business districts, enjoy steadier year-round occupancy. Office workers and students need housing all year, not just in July.

    For investors, the choice depends on your risk tolerance. Beachfront offers high rewards during peak season but requires managing vacancies. City-center provides predictable cash flow but with lower per-night returns.

    Lifestyle: Waves vs. City Lights

    The lifestyle differences are stark. Beachfront living means waking up to ocean views, stepping onto the sand, and hearing waves instead of traffic. It’s quieter, with more privacy and natural light. But daily amenities are limited—you’ll likely need to drive 10–20 minutes for groceries, restaurants, or healthcare. Commutes to work can stretch 30–60 minutes each way.

    City-center living puts you in the heart of the action. Walk to work, grab dinner at a new bistro, or catch a show. Public transit and bike lanes make car ownership optional. The downside? Noise from traffic, sirens, and nightlife, plus less personal space. If you thrive on social energy and cultural events, the city has the edge. If you crave tranquility and outdoor activity, the beach wins.

    The Remote Work Shift

    The pandemic upended the calculus. With remote work, many people flocked to beachfront towns, driving up prices in places like Sarasota, FL, and San Clemente, CA. But as companies push return-to-office, some demand has swung back. Hybrid work schedules have permanently expanded the viable radius—you can live by the beach and commute a few days a week.

    Remote workers often find beachfront ideal if they have stable income and can handle the isolation. Coworking spaces are growing in coastal towns, but they’re still limited. City centers offer better internet infrastructure and networking opportunities, plus backup employment options if your job situation changes.

    Family Considerations: Schools and Services

    Families face a different set of trade-offs. Beachfront towns often have weaker school districts—they’re tourist economies, not education hubs. Pediatric services may be limited, and extracurricular activities might require long drives. City centers typically offer better schools, hospitals, and childcare options. But urban living often means smaller apartments and less outdoor space for kids to play.

    If you have school-age children, the city center likely wins on practical grounds. For retirees or childless couples, the beach’s serenity might outweigh the lack of services.

    Climate Risk and Future Values

    Climate change is reshaping beachfront markets. Rising sea levels and stronger storms are beginning to discount values in high-risk zones, especially Florida’s Atlantic and Gulf coasts. Some buyers are pivoting to ‘coastal-adjacent’ inland areas that offer proximity to the beach without the flood risk. Meanwhile, city centers face less climate risk but are more vulnerable to economic downturns.

    Insurance costs are a key indicator—if insurers are fleeing, that’s a red flag. Always check flood maps and talk to local agents before buying beachfront.

    Which One Is Right for You?

    There’s no universal answer. Beachfront is perfect for those who value wellness, privacy, and a slower pace. The mental health benefits of ocean proximity are real—reduced stress, better sleep. But you must be comfortable with longer drives and seasonal crowds.

    City center suits career-driven professionals, families, and anyone who thrives on convenience. The walkability and cultural access are unbeatable, and the steady rental market provides financial stability. But you’ll trade natural scenery for urban noise.

    Consider your work situation, family needs, and how you want to spend your weekends. If you’re torn, try renting in each location for a few months. Experience beats speculation.

    Choosing between beachfront and city center is a deeply personal decision. The numbers can guide you, but your lifestyle will ultimately decide. Weigh the costs, the commute, the schools, and the view. The right choice is the one that makes you feel at home—whether that’s to the sound of waves or the hum of the city.

    Summary

    • Beachfront properties cost 30–100% more per square foot and have 2–5x higher insurance, but offer scarcity-driven appreciation and high seasonal rental income.
    • City center living provides shorter commutes, year-round rental demand, and access to amenities, but often with higher HOA fees and less natural scenery.
    • Beachfront offers wellness benefits like reduced stress and better sleep, but may lack quality schools and healthcare in tourist towns.
    • Remote work has expanded the feasibility of beachfront living, but city centers still offer better infrastructure and employment backup.
    • Climate change is beginning to impact beachfront values, particularly in high-risk coastal zones.

    FAQ

    Q: Is beachfront living a good investment?
    A: Yes, if you can handle the higher upfront costs and insurance. Beachfront properties have historically appreciated well due to limited supply. However, consider climate risks and seasonal rental fluctuations.

    Q: Are city center rentals more profitable than beachfront?
    A: City center rentals typically offer steadier occupancy, especially in business districts, but lower nightly rates. Beachfront can yield 2–3x higher nightly rates but only during peak season.

    Q: Which is better for families?
    A: City center usually wins for families due to better schools, healthcare, and childcare options. Beachfront towns often have weaker school districts and fewer services.

    Q: How does remote work affect the choice?
    A: Remote work makes beachfront living more feasible, as you don’t need to commute daily. However, city centers still offer better internet infrastructure and networking opportunities.

    Q: What are the risks of beachfront properties?
    A: Higher insurance costs, climate change risks like sea-level rise and storms, and potential for seasonal business downturns in tourist-dependent areas.
  • The AI Bubble Is Popping; We Just Don’t Know It Yet

    The AI Bubble Is Popping; We Just Don’t Know It Yet

    In late 2022, ChatGPT burst onto the scene, igniting a global frenzy. Venture capital poured into AI startups, tech giants raced to build massive data centers, and the stock market rewarded anything with an ‘AI’ label. But beneath the surface, a different story is unfolding. The AI bubble is not bursting with a bang; it’s leaking slowly, and most of us haven’t noticed yet.

    This article explores the signs that the AI boom is deflating, from overvalued companies and soaring costs to enterprise fatigue and open-source competition. We’ll look at why the bubble is deflating quietly, what it means for the industry, and how we can navigate the coming correction. By understanding the dynamics at play, we can separate hype from reality and make informed decisions about AI’s future.

    The Hype Cycle and the Quiet Leak

    Every major technological revolution follows a pattern: excitement, overinvestment, disillusionment, and eventual maturity. The AI boom is no different. The initial euphoria, sparked by ChatGPT’s release, led to a massive influx of capital. Companies with little more than a chatbot prototype received billion-dollar valuations. But the hype is cooling. The bubble is not popping with a dramatic crash; it’s leaking slowly, like a tire with a small puncture. Layoffs, down-rounds, and quiet shutdowns are happening now, but the headline indices—like the NASDAQ—are still buoyed by a few mega-cap stocks, masking the underlying weakness.

    The Valuation-Reality Gap

    One of the clearest signs of a bubble is when valuations far outstrip actual revenue. Many AI startups and public companies trade at multiples that defy traditional financial logic. For example, OpenAI and Anthropic have valuations in the tens of billions, yet their revenue is a fraction of that. Nvidia, the chipmaker, has seen its stock soar, but its success is tied to a spending spree that may not last. The gap between what companies are worth and what they actually earn is a classic bubble indicator. When the music stops, those with weak fundamentals will suffer the most.

    The Costly Reality of AI

    Training a frontier AI model costs hundreds of millions, sometimes billions, of dollars. And the costs don’t stop there. Running these models—known as inference—requires massive computing power, and the electricity to power it. For many AI companies, the cost of serving each user exceeds the subscription price they charge. This is unsustainable. As costs remain high and revenue growth slows, the financial pressure mounts. The ‘picks and shovels’ logic—that selling infrastructure to miners is a safe bet—works only as long as the miners keep digging. When they stop, the shovel sellers suffer too.

    Revenue Concentration and Fragility

    The AI ecosystem is dangerously concentrated. A significant portion of AI revenue flows to a small number of infrastructure providers, especially Nvidia. If those companies’ spending slows, the entire ecosystem feels the shock. This fragility is a hallmark of bubbles. In the dot-com era, telecom companies overbuilt fiber-optic networks, expecting demand that never materialized. When the bubble burst, the overcapacity led to bankruptcies. AI’s infrastructure buildout—data centers, GPUs, energy contracts—is similar. The spending is already committed, but if demand softens, the overcapacity will be a burden.

    Enterprise Adoption Fatigue

    Despite the hype, many enterprises are struggling to see a return on their AI investments. Pilot projects often fail to scale, and AI tools see high churn rates. A recent survey found that most companies have not seen significant productivity gains from AI. This echoes the ‘productivity paradox’ of the 1980s and 1990s, when computers were everywhere but didn’t show up in economic statistics. The gap between promise and reality is causing a backlash. CFOs are asking tough questions about ROI, and budgets are being scrutinized. The era of ‘AI for AI’s sake’ is ending.

    Open-Source Competition and Price Compression

    Another factor deflating the bubble is the rise of open-source models. Llama, Mistral, and Qwen have shown that capable AI can be built and distributed freely. This compresses pricing power for commercial providers. Why pay for a proprietary model when a free one works almost as well? The result is a race to the bottom on price, squeezing margins. This is good for consumers but bad for startups that relied on high margins to justify their valuations. The open-source wave is a silent killer, eroding the moats that AI companies thought they had.

    The ‘We Don’t Know It Yet’ Factor

    So why haven’t we seen a crash? Because the bubble is deflating unevenly. The stock market is still propped up by a handful of mega-cap tech companies—Microsoft, Apple, Nvidia—that have diversified revenue streams. But beneath them, the AI sector is bleeding. Venture capital funding for AI startups has dropped, and many are taking down-rounds at lower valuations. The ‘we don’t know it yet’ framing is about the lag between reality and perception. By the time the headline indices reflect the correction, the damage will already be done.

    Historical Parallels: The Dot-Com Bubble

    The dot-com bubble of the late 1990s is the most instructive parallel. Then, as now, there was a belief that ‘this time is different.’ Companies with no earnings and no clear path to profitability were valued in the billions. The infrastructure buildout—fiber-optic networks, data centers—was massive. When the bubble burst, the NASDAQ fell 78% from its peak. Many companies went bankrupt, but the internet itself survived and thrived. The same will likely happen with AI. The technology is real and transformative, but the current valuations are not. A correction is inevitable, and it will be painful for those who overextended.

    The Road Ahead: A Correction, Not a Crash?

    Some argue that this is not a bubble but a correction—a necessary shakeout that will separate the wheat from the chaff. The AI sector will experience a de-rating of 30–50% off peak valuations, but not a systemic collapse. The technology will survive, and the winners will emerge stronger. This is the ‘trough of disillusionment’ in the Gartner Hype Cycle. It’s a normal part of the cycle, and it’s already happening in specific niches. Generative AI content tools, for example, have seen price wars and consolidation. The same is now spreading to enterprise AI and infrastructure.

    What Should You Do?

    For businesses and investors, the key is to be cautious. Don’t overpay for AI hype. Focus on fundamentals: revenue, profitability, and real-world use cases. For enterprises, don’t adopt AI just because it’s trendy. Ensure it delivers measurable ROI. For individuals, don’t panic. The AI revolution is real, but it will take time to mature. The bubble is popping, but that doesn’t mean AI is going away. It means the industry is growing up.

    Conclusion

    The AI bubble is popping, but we just don’t know it yet. The signs are all around us: overvaluation, high costs, revenue concentration, enterprise fatigue, and open-source competition. The correction is already underway, even if the headline indices haven’t caught up. But this is not the end of AI. It’s the end of the hype. The technology will survive, and the winners will be those who focus on sustainable value creation. As the bubble deflates, we have an opportunity to build a more realistic and resilient AI industry.

    The AI bubble is deflating, but this is not a death knell for the technology. It’s a necessary correction that will separate hype from reality. By understanding the signs—valuation gaps, cost pressures, and adoption fatigue—we can navigate the coming changes with clarity. The future of AI is bright, but it will be built on solid foundations, not speculative froth.

    Summary

    • The AI bubble is deflating slowly, not crashing, and the signs are already visible in layoffs, down-rounds, and quiet shutdowns.
    • Valuations for many AI companies far exceed their actual revenue, a classic bubble indicator.
    • The high costs of training and running AI models, combined with revenue concentration in a few infrastructure providers, create fragility.
    • Enterprise adoption is faltering as ROI fails to materialize, echoing the productivity paradox of earlier tech booms.
    • Open-source models are compressing pricing power, eroding the moats of commercial AI providers.

    FAQ

    Q: Is the AI bubble really popping?
    A: Yes, but it’s a slow leak, not a sudden burst. Many AI startups are facing layoffs, down-rounds, and closures, even though the stock market hasn’t fully reflected this yet.

    Q: What are the main signs of the bubble deflating?
    A: Key signs include overvaluation relative to revenue, high training and inference costs, revenue concentration in a few companies like Nvidia, enterprise adoption fatigue, and the rise of open-source models that undercut pricing.

    Q: Will AI technology survive the bubble?
    A: Absolutely. Like the internet after the dot-com crash, AI will continue to evolve and transform industries. The bubble is about valuations, not the technology itself.

    Q: What should businesses do in response?
    A: Focus on real-world use cases and measurable ROI. Avoid adopting AI just for hype. Be cautious with investments and prioritize fundamentals over speculation.

    Q: How long will the correction last?
    A: It’s hard to say, but historical parallels suggest a de-rating of 30–50% could occur over a few years. The industry will likely consolidate, and the strongest players will emerge.

  • FIFA Chief Gianni Infantino Abandons $20 Billion Private Investment Plan Amid Widespread Opposition

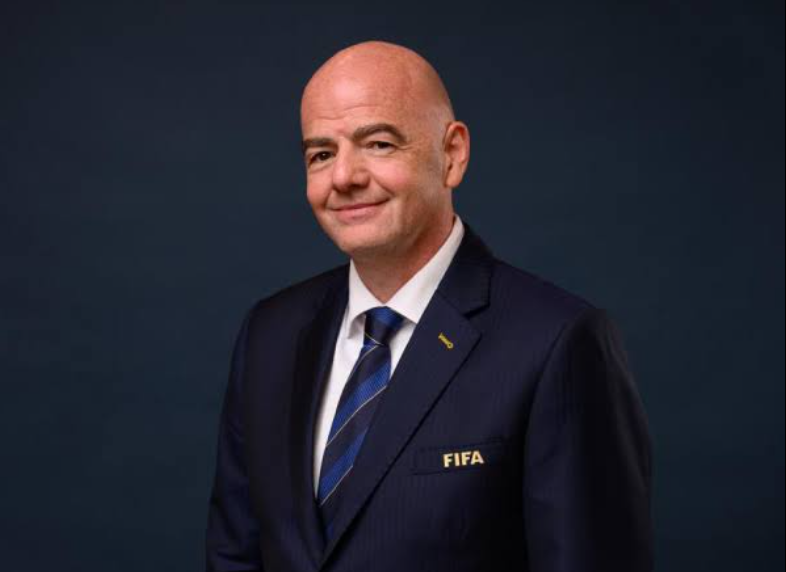
    FIFA Chief Gianni Infantino Abandons $20 Billion Private Investment Plan Amid Widespread Opposition

    In a dramatic reversal, FIFA President Gianni Infantino has officially scrapped the proposed ‘FIFA Forward Enterprise,’ a $20 billion private investment vehicle that would have taken control of the commercial rights to the World Cup and other FIFA events. The announcement, made late Friday, comes after months of mounting criticism from football governing bodies, player unions, and transparency watchdogs, who argued the plan threatened the sport’s integrity and governance.

    The decision marks a significant setback for Infantino, who had championed the plan as a visionary way to secure long-term funding for global football development. However, the proposal’s lack of consultation and its potential to hand significant influence to private investors proved to be its undoing, creating deep divisions within the football community.

    As FIFA reverts to its traditional commercial model, the episode raises questions about Infantino’s leadership and the future direction of the sport’s global governing body.

    The Plan and Its Demise

    The FIFA Forward Enterprise was first floated in late 2024 as a mechanism to ‘de-risk’ FIFA’s revenue model and accelerate investment in football development, particularly in underserved regions. The structure would have created a new corporate entity backed by private investors, including sovereign wealth funds and private equity firms, to manage and monetize FIFA’s event rights. Proponents argued it would provide financial certainty and allow FIFA to invest without relying solely on traditional broadcast and sponsorship cycles.

    However, the plan quickly drew fire. Critics, including UEFA and other European football bodies, viewed it as a power grab that would undermine the traditional governance of the sport. Player unions like FIFPRO raised concerns about commercial pressures dictating match calendars, while transparency watchdogs warned of a ‘shadow FIFA’ with little accountability. The lack of consultation with national federations and confederations, many of whom learned of the plan through press leaks, further fueled opposition.

    In his statement, Infantino acknowledged that the project had ‘created divisions’ and said it was clear that it was not the right path forward. He emphasized that FIFA would continue with its existing commercial model, selling rights on a cycle-by-cycle basis, and reaffirmed his commitment to global football development.

    Governance and Conflict of Interest Concerns

    At the heart of the controversy were governance and conflict of interest issues. Handing commercial rights to a private entity would have stripped FIFA’s member associations of oversight and accountability, critics argued. The structure would have given private investors significant influence over FIFA’s flagship events, potentially prioritizing profit over the sport’s integrity. This historical baggage, reminiscent of the corruption scandals of the 2010s, made the plan a lightning rod for criticism.

    Infantino’s camp had argued that the plan was a visionary move to secure long-term funding, especially for Africa, Asia, and the Americas. Some smaller federations, particularly those with limited resources, were reportedly open to the idea if it meant guaranteed funding. However, the overwhelming opposition from powerful stakeholders and the public ultimately sealed its fate.

    Implications for FIFA and Infantino

    The collapse of the FIFA Forward Enterprise is a significant blow to Infantino, who has faced controversy throughout his tenure, including governance issues, human rights concerns related to the 2022 Qatar World Cup, and his push for expanded competitions. While he was re-elected unopposed in 2019 and 2023, this episode may embolden his critics and raise questions about his leadership style.

    FIFA’s financial position remains strong, with reserves exceeding $4 billion, which raises questions about why such a large external investment was needed in the first place. The decision to abandon the plan may be seen as a victory for those who advocate for transparency and accountability in football governance.

    Reactions and Next Steps

    Reactions to the announcement have been mixed. European football bodies and transparency watchdogs have welcomed the decision, viewing it as a necessary correction. FIFPRO expressed relief that player welfare concerns were heeded. However, some smaller federations that had hoped for guaranteed funding may be disappointed.

    Moving forward, FIFA will need to rebuild trust and find alternative ways to support global football development. The episode serves as a reminder of the delicate balance between commercial interests and the sport’s integrity, a challenge that will continue to shape FIFA’s future.

    The abandonment of the $20 billion FIFA Forward Enterprise marks a pivotal moment for Gianni Infantino’s presidency and for FIFA as a whole. While the plan was framed as a visionary financial strategy, its lack of transparency and consultation ultimately made it untenable. As FIFA returns to its traditional commercial model, the focus now shifts to how Infantino will navigate the ongoing tensions between modernization and governance, and whether he can restore confidence among the sport’s diverse stakeholders.

    Summary

    • FIFA President Gianni Infantino has scrapped the proposed $20 billion FIFA Forward Enterprise investment vehicle.
    • The plan would have given private investors control over commercial rights to the World Cup and other events.
    • Critics cited governance concerns, lack of consultation, and potential conflicts of interest.
    • The decision is a setback for Infantino, who had championed the plan as a way to secure long-term funding.
    • FIFA will continue with its existing commercial model, selling rights on a cycle-by-cycle basis.

    FAQ

    Q: What was the FIFA Forward Enterprise?
    A: It was a proposed $20 billion private investment vehicle that would have taken control of the commercial rights to FIFA’s events, including the World Cup, to provide financial certainty and fund global football development.

    Q: Why was the plan controversial?
    A: Critics argued it would strip FIFA’s member associations of oversight, give private investors too much influence, and lacked consultation with key stakeholders, reviving memories of past corruption scandals.

    Q: Who opposed the plan?
    A: European football bodies like UEFA, player unions like FIFPRO, transparency watchdogs, and many fans and media outlets opposed it, citing governance and integrity concerns.

    Q: What happens now?
    A: FIFA will continue with its traditional commercial model, selling broadcasting and sponsorship rights on a cycle-by-cycle basis, and will need to find alternative ways to support development.

    Q: What does this mean for Gianni Infantino?
    A: The collapse is a significant setback for Infantino, potentially emboldening critics and raising questions about his leadership and the future direction of FIFA.