Tag: financial planning

  • The 50-Year Deadline: 5 Moves That Matter Most Before Midlife

    The 50-Year Deadline: 5 Moves That Matter Most Before Midlife

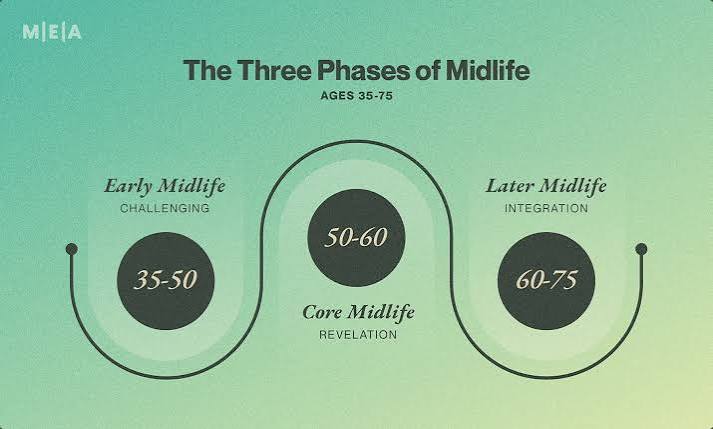
    Turning 50 isn’t a cliff—it’s a crossroads. For most people in developed countries, life expectancy hovers around 78 to 82, which makes 50 the rough halfway point. The decisions you make in the next few years will shape not just your 50s, but the three decades that follow. This isn’t about morbid countdowns; it’s about using a clear deadline to force clarity.

    A “mortality checklist” borrows from stoic philosophy—memento mori, remember you will die—not to scare you, but to help you prioritize. When you know time is finite, you stop drifting and start choosing. Below are the five moves that matter most before you hit the half-century mark, grounded in practical research and expert consensus.

    1. Get Your Financial House in Order

    At 50, you’re likely in your peak earning years—the window between 45 and 54 when income typically tops out. But the Federal Reserve reports that the median retirement savings for Americans aged 45–54 is only about $100,000 to $150,000. That’s far short of the 5–7 times your annual salary that most financial planners recommend by this age.

    The good news: age 50 unlocks catch-up contributions. In the U.S., you can contribute an extra $7,500 to a 401(k) and an extra $1,000 to an IRA each year. That’s a powerful tool, but it only helps if you use it.

    Before 50, also tackle debt. High-interest credit cards and personal loans eat into compounding returns. And if you haven’t bought life insurance yet, do it now—premiums rise sharply with age, and health issues that emerge in your 50s can make coverage expensive or impossible.

    2. Establish a Health Baseline

    Your 50-year-old body is the product of your 40s; your 60s will be shaped by your 50s. Chronic diseases like heart disease, diabetes, and cancer often surface in the 50s, but many are preventable with early action.

    Start with a full physical and updated screenings. Colonoscopies now begin at 45, and mammograms, prostate checks, and bone density scans become routine. If you haven’t had a stress test or blood work panel recently, make it a priority.

    Then, take stock of lifestyle. The CDC reports that 6 in 10 U.S. adults have a chronic disease, many preventable. You don’t need a radical overhaul—consistent sleep, a Mediterranean-style diet, and regular movement can reverse years of neglect. The key is to start now, not at 60.

    3. Repair Relationships and Build Your Support Network

    Psychologist and palliative care nurse Bronnie Ware’s book The Top Five Regrets of the Dying found that the most common regret is, “I wish I’d had the courage to live a life true to myself, not the life others expected of me.” The second most common? “I wish I hadn’t worked so hard.” The third: “I wish I’d had the courage to express my feelings.”

    Those regrets point to relationships. Before 50, mend estrangements where possible—or at least make peace with them. Deepen the bonds that matter, whether with a partner, children, or close friends. Also, intentionally build a support network beyond family: a few trusted confidants, a community group, or a mentor. These connections buffer against the isolation that can creep in during midlife transitions.

    4. Put Your Legacy in Writing

    This is the most literal “mortality preparation,” and it’s the one people avoid most. But dying without a will or healthcare proxy leaves your family with legal battles and emotional turmoil. According to a 2023 Caring.com survey, only 34% of U.S. adults have a will.

    Before 50, take these steps:
    – Write or update your will and trust.
    – Designate a healthcare proxy and living will.
    – Buy life insurance if you have dependents.
    – Inventory your digital assets—passwords, social media accounts, cryptocurrency—and store them securely where someone can find them.
    – Have the conversation with your family about end-of-life wishes. It’s uncomfortable, but it’s a gift of clarity.

    5. Do One Thing That Scares You—or That You’ll Never Do at 60

    This is the bucket-list item, but it’s not about tourism. It’s about confronting a fear or pursuing a physical goal while your body still cooperates. High-adventure travel, learning to surf, running a marathon, or even taking up a demanding craft—these are best done before 50, when recovery is faster and energy is higher.

    But the deeper purpose is psychological. Psychologists note that turning 50 often triggers a “midlife review,” where you ask, “Is this the life I wanted?” That question is healthy. Use it to audit your purpose, not just your passport.

    If you can’t afford a grand adventure, choose something equally meaningful: learn an instrument, write a letter to your future self, or volunteer for a cause you care about. The point is to act intentionally, not to drift into the next decade.

    Fifty is not a point of no return. Many of these items can be done at 55 or 60—but they won’t be, because life fills the space you give it. The checklist is a tool for prioritization, not a countdown to doom. Start with one item this month, and let the deadline work for you.

    Summary

    • Financial readiness: Peak earning years, catch-up contributions, pay off debt, buy life insurance.
    • Health baseline: Full physical, screenings, lifestyle changes—your 50s shape your 60s.
    • Relationship repair: Mend estrangements, deepen bonds, build a support network.
    • Legacy planning: Will, healthcare proxy, digital assets, and family conversations.
    • Experiential goal: Do one physically demanding or fear-confronting thing while you can.

    FAQ

    Q: Is the ‘before 50’ deadline really necessary?
    A: No, it’s not a hard cutoff—life doesn’t end at 50. But it’s a useful psychological trigger. People act more decisively when there’s a clear temporal boundary, and starting earlier gives you compounding advantages in health, finances, and relationships.

    Q: What if I can’t afford big-ticket items like travel or early retirement?
    A: The checklist is adaptable. The experiential item can be free or low-cost, like learning a new skill or volunteering. Financial readiness is about debt and savings, not luxury. Prioritize what matters most for your situation.

    Q: I’m already over 50. Is it too late?
    A: Not at all. The list is about prioritization, and many items can be done at any age. The sooner you start, the more benefit you’ll get, but it’s never too late to make a will, improve health, or mend a relationship.

    Q: Why is this called a ‘mortality checklist’? Isn’t that morbid?
    A: The term borrows from memento mori—remembering you’ll die to live better. It’s not about doom; it’s about using finite time to focus on what truly matters. The tone is pragmatic, not fearful.

    Q: What’s the single most important item?
    A: For most people, financial readiness and health are the foundations—they affect everything else. But if you’re already healthy and debt-free, legacy planning might be the most urgent, since it protects your loved ones.
  • Whole Life Insurance: The Complete Guide to Its Pros and Cons

    Whole Life Insurance: The Complete Guide to Its Pros and Cons

    Whole life insurance is often marketed as the ultimate financial safety net—a policy that protects your family for life while building a cash reserve you can tap into. But it’s also one of the most debated financial products, with critics calling it a poor investment and proponents praising its guarantees. So, is it a smart cornerstone of your financial plan or an expensive mistake? This guide breaks down the real pros and cons, the mechanics, and who might actually benefit from whole life insurance.

    What Is Whole Life Insurance?

    Whole life insurance is a type of permanent life insurance. Unlike term life, which covers you for a set period (like 20 or 30 years), whole life is designed to last your entire lifetime, as long as you pay the premiums. It combines two components:

    • Death benefit: A tax-free payout to your beneficiaries when you die.
    • Cash value: A savings-like account that grows over time on a tax-deferred basis.

    Your premiums are fixed—they never increase as you age or if your health declines. A portion of each premium goes toward the insurance cost, and the rest goes into the cash value, which the insurer invests. The cash value grows at a guaranteed minimum rate (often 2–4%), and many policies also pay dividends (not guaranteed) that can be used to reduce premiums, buy more coverage, or accumulate interest.

    The Pros: Why People Choose Whole Life

    1. Lifelong Coverage and Guaranteed Death Benefit

    The most obvious advantage is that your beneficiaries are guaranteed a payout no matter when you die—whether it’s 5 years or 50 years from now. This provides peace of mind for those who want to ensure final expenses, debts, or legacy goals are covered.

    2. Cash Value That Grows Tax-Deferred

    The cash value grows without being taxed each year. You can borrow against it or withdraw it, though withdrawals above your basis may be taxable. This can be a useful emergency fund or supplemental retirement income source.

    3. Fixed Premiums

    Once you buy a policy, your premium is locked in for life. This is a hedge against future health issues—if you develop a serious condition later, your premium won’t change.

    4. Forced Savings Discipline

    For people who struggle to save, the mandatory premium acts as a disciplined savings mechanism. You’re effectively building a cash reserve without having to think about it.

    5. Estate Planning and Business Uses

    Whole life can be a strategic tool for high-net-worth individuals. It can provide liquidity to pay estate taxes, equalize inheritances among heirs, or fund buy-sell agreements in business partnerships. The death benefit is generally income-tax-free to beneficiaries.

    6. Creditor Protection

    In many states, the cash value and death benefit are protected from creditors, making it a safe haven for assets in lawsuits or bankruptcy.

    The Cons: Why Critics Say ‘Buy Term and Invest the Difference’

    1. High Cost

    Whole life premiums are typically 5 to 15 times more expensive than term life for the same death benefit. For example, a healthy 35-year-old male might pay $300–$600 per month for a $500,000 whole life policy, versus $30–$50 per month for a 20-year term policy. That’s a significant opportunity cost.

    2. Low Returns on Cash Value

    The cash value grows at a modest rate—historically around 5–7% including dividends, but the guaranteed rate is often just 2–4%. Compare that to the long-term average of the S&P 500 at about 10%. Over decades, the difference in wealth accumulation is massive.

    3. Complexity and Lack of Transparency

    Policy illustrations are notoriously complicated, with projections that can be misleading. The mix of guaranteed and non-guaranteed values, dividends, and surrender charges makes it hard to compare policies or understand what you’re really getting.

    4. Surrender Charges and Early Exit Penalties

    If you cancel your policy within the first 10–15 years, you’ll face surrender charges that can eat into your cash value. In the early years, you may get back far less than you paid in. This makes whole life illiquid and risky if your financial situation changes.

    5. High Commissions and Sales Pressure

    Agents often earn commissions of 50–100% of your first-year premium. This creates a strong incentive to sell whole life even when it’s not the best fit. Many consumers are sold on the ‘investment’ angle without fully understanding the costs.

    6. Opportunity Cost

    The ‘buy term and invest the difference’ strategy is a powerful alternative. If you invest the premium savings in a diversified portfolio, you could end up with far more wealth over the long run—even after paying for term coverage.

    Who Should Consider Whole Life?

    Whole life isn’t inherently good or bad—it’s about fit. It may make sense for:

    • High-net-worth individuals needing estate planning tools.
    • Business owners using it for key-person insurance or buy-sell agreements.
    • People with special-needs dependents who require guaranteed lifelong coverage.
    • Those who have maxed out other tax-advantaged accounts and want a conservative, guaranteed asset.
    • Individuals who lack savings discipline and value the forced savings aspect.

    On the flip side, if you’re a young professional with limited income, or you’re looking for high growth, term life plus investing is likely a better route.

    Alternatives to Whole Life

    • Term life insurance: Pure protection for a set period, much cheaper, and ideal for covering income replacement during working years.
    • Indexed universal life (IUL): A type of permanent insurance with cash value linked to a stock index, offering more upside potential but also more risk.
    • Variable universal life (VUL): Cash value is invested in sub-accounts like mutual funds, offering high growth potential but no guarantees.
    • Investing in a taxable brokerage account: If you’re disciplined, investing the premium difference in low-cost index funds can yield higher returns.

    The Bottom Line

    Whole life insurance is a complex product that serves a specific niche. It’s not a good ‘investment’ in the traditional sense—the returns are low and fees are high. But for certain people, the guarantees and unique features outweigh the costs. Before buying, ask yourself: Do I need lifelong coverage? Have I maxed out my retirement accounts? Am I comfortable with low returns for the sake of safety? If you answer ‘no’ to the first two and ‘no’ to the third, you’re likely better off with term insurance and investing the difference.

    Whole life insurance is a tool, not a one-size-fits-all solution. It offers guaranteed lifelong coverage and a tax-deferred cash value, but at a steep price and with modest growth. For most people, a combination of term life insurance and disciplined investing will build more wealth. However, for those with complex estate planning needs or a desire for guaranteed, creditor-protected assets, whole life can be a valuable piece of a broader financial strategy. The key is to understand exactly what you’re buying, compare costs, and consult with a fee-only financial advisor who isn’t incentivized by commissions.

    Summary

    • Whole life insurance provides lifelong coverage with a guaranteed death benefit and a tax-deferred cash value component.
    • Premiums are fixed but typically 5–15x higher than term life for the same coverage.
    • Cash value grows at a low guaranteed rate (2–4%) plus potential dividends, but historical returns lag stock market averages.
    • Surrender charges in the early years can result in losses if you cancel.
    • It’s best suited for high-net-worth estate planning, business needs, or those who value forced savings over investment returns.

    FAQ

    Q: Is whole life insurance a good investment?
    A: Generally, no. The cash value grows slowly (2–4% guaranteed) and fees are high. Over the long term, investing the premium difference in a diversified portfolio typically yields higher returns. Whole life is primarily insurance, not an investment.

    Q: Can I borrow against my whole life policy’s cash value?
    A: Yes, you can take a policy loan. The loan accrues interest, and if unpaid, it reduces the death benefit. It’s a flexible source of funds, but be aware of the impact on your beneficiaries.

    Q: What happens if I cancel my whole life policy?
    A: You receive the cash value minus any surrender charges, which are highest in the first 10–15 years. In early years, you may get back less than you paid in premiums.

    Q: How does whole life compare to term life?
    A: Term life is much cheaper and covers you for a set period (e.g., 20 years), with no cash value. Whole life covers you for life and builds cash value, but at a significantly higher cost.

    Q: Who should buy whole life insurance?
    A: It’s most suitable for high-net-worth individuals needing estate planning, business owners with buy-sell agreements, or those who want guaranteed lifelong coverage and have maxed out other tax-advantaged accounts. For most others, term life plus investing is more cost-effective.