Tag: e-commerce

  • Why 48% of Consumers Trust AI Recommendations (and What the Other 52% Need)

    Why 48% of Consumers Trust AI Recommendations (and What the Other 52% Need)

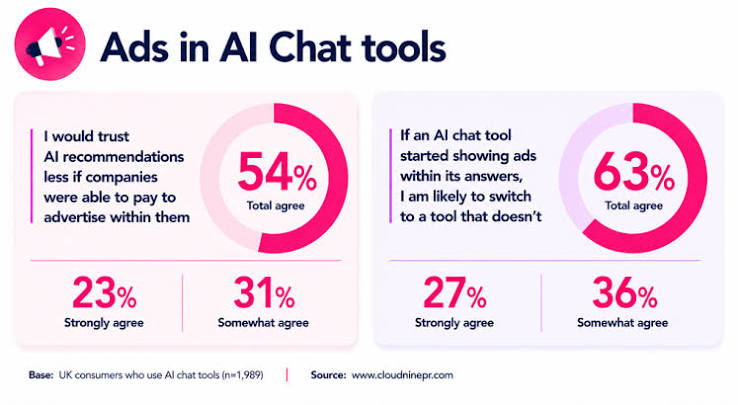
    Nearly half of consumers say they would trust an AI to recommend products. That’s 48% — a figure that could reshape e-commerce, marketing, and the very nature of shopping. But what does that number actually mean? It’s not a blanket endorsement of AI. It’s a conditional, context-dependent trust that varies by product, platform, and person.

    This article unpacks the 48% statistic, explores why the other 52% remain skeptical, and looks at what it takes to build or break consumer trust in AI recommendations. From the evolution of recommendation engines to the rise of generative AI, we’ll examine the factors that drive trust and the pitfalls that erode it.

    The Anatomy of the 48%

    The 48% figure comes from a survey asking consumers if they’d trust an AI to recommend products. It’s a significant minority, but not a majority. To understand what this number really means, we need to look at the conditions under which trust is granted.

    Trust in AI is conditional. Consumers are more likely to trust AI for low-stakes, low-cost purchases — a book, a movie, a pair of socks — than for high-stakes ones like a car, a medical device, or financial advice. The stakes matter. A wrong book recommendation is a minor annoyance; a wrong car recommendation is a costly mistake.

    Context also plays a role. Trust in a recommendation algorithm embedded in a familiar platform (like Netflix or Amazon) may be higher than trust in a standalone AI chatbot. Consumers have years of experience with Netflix’s suggestions, many of which have been spot-on. That track record builds trust.

    From Invisible Algorithms to Visible AI

    Recommendation systems have been around since the 1990s, when Amazon introduced collaborative filtering — “customers who bought this also bought that.” These early algorithms were invisible, operating behind the scenes. Consumers didn’t think about them; they just saw suggestions.

    The rise of deep learning and neural networks in the 2010s made recommendations hyper-personalized, but still opaque. Netflix, Spotify, and TikTok use AI to serve content tailored to individual tastes, often with uncanny accuracy.

    The game changed in 2022 with generative AI. ChatGPT and similar tools made AI visible and conversational. Instead of passively receiving suggestions, consumers now ask an AI directly: “What should I buy for a camping trip?” This shift changes the trust calculus. When AI is a visible agent, consumers scrutinize it more.

    Why Do People Trust AI? The Key Drivers

    Research points to several factors that build trust in AI recommendations:

    • Transparency: When users understand why a recommendation was made, they trust it more. “Because you watched The Crown” is more persuasive than a mysterious algorithm.
    • Control: Giving users the ability to adjust, override, or dismiss AI suggestions increases trust. A recommendation is a suggestion, not a command.
    • Track record: Past accuracy builds trust. If an AI consistently recommends good books, you’ll trust it more over time.
    • Brand reputation: Trust in the platform hosting the AI transfers to the AI itself. If you trust Amazon, you’re more likely to trust Amazon’s AI.
    • Perceived stakes: As mentioned, low-risk items generate higher trust. You’ll let AI pick a movie, but not a surgeon.

    Why Do the Other 52% Say No?

    Skepticism is not irrational. The “black box” problem is real: consumers can’t see how AI arrives at its recommendations. This opacity breeds distrust. Here are the main concerns:

    • Manipulation: AI may be optimized for seller profit, not consumer benefit. If a recommendation serves the retailer’s bottom line more than your needs, it’s not trustworthy.
    • Bias: Algorithms trained on historical data can perpetuate existing biases — racial, gender, or socioeconomic. This can lead to unfair or discriminatory recommendations.
    • Privacy: Recommendations require vast amounts of personal data. Many consumers are uncomfortable with the surveillance required to power these systems.

    These are legitimate concerns, and they explain why a majority of consumers remain wary.

    The Generational and Cultural Divide

    Trust in AI is not monolithic. Younger consumers (18–34) grew up with algorithmic feeds and are generally more trusting of AI. Older consumers (55+) often prefer human judgment and established brands. The 48% figure likely skews younger and more digitally native.

    Culture also matters. Research shows that trust in AI varies by country — higher in East Asia, lower in parts of Europe and North America. Collectivist cultures may value “what people like me buy,” while individualist cultures want “what’s best for me.” These differences shape how recommendations are received.

    The Optimistic and Skeptical Views

    The Optimistic View: AI as a Trusted Advisor

    AI can process far more data than any human, leading to better, more personalized recommendations. In niche categories — indie music, obscure books, specialized gear — AI often outperforms human curators. As AI becomes more explainable (the field of XAI), trust is likely to increase.

    The Skeptical View: The Black Box Problem

    Consumers cannot verify how AI arrives at recommendations, creating an inherent trust deficit. The 52% majority likely includes those who fear manipulation or loss of autonomy. They want to know: Is this AI working for me, or for the seller?

    What Does This Mean for Businesses?

    For retailers and platforms, the 48% figure represents a huge opportunity. AI-driven recommendations already drive an estimated 35% of Amazon’s revenue. But to win over the skeptical majority, businesses must address the trust deficit.

    Transparency is key. Explain why a recommendation was made. Give users control — let them tune the AI’s parameters or opt out entirely. Build a track record of accurate, beneficial recommendations. And above all, ensure the AI is aligned with the consumer’s interests, not just the seller’s.

    Regulation is also coming. The EU AI Act (2024) and similar frameworks mandate transparency in AI-driven decisions, including recommendations. Businesses that embrace transparency now will be ahead of the curve.

    The Future of Trust in AI Recommendations

    As AI becomes more explainable and consumers gain more control, trust is likely to grow. The 48% may become 60% or 70% over time. But trust is fragile. One high-profile failure — a harmful recommendation, a privacy breach — could set back progress significantly.

    The path forward is clear: build AI that is transparent, controllable, and genuinely beneficial. The 48% are ready to trust; the 52% are waiting for a reason to.

    The 48% figure is a starting point, not a finish line. It shows that a substantial portion of consumers are open to AI-driven recommendations, but trust is conditional and easily lost. For businesses, the message is simple: earn trust through transparency, control, and alignment with consumer interests. For consumers, the message is equally clear: AI can be a powerful tool, but it’s up to you to decide when to trust it.

    Summary

    • 48% of consumers trust AI to recommend products, but trust is conditional and context-dependent.
    • Trust is higher for low-stakes, low-cost purchases and on familiar platforms with a good track record.
    • Key trust drivers: transparency, control, track record, brand reputation, and perceived stakes.
    • The skeptical 52% worry about manipulation, bias, and privacy.
    • Younger and more digitally native consumers are more trusting; cultural and geographic factors also play a role.
    • Businesses can build trust by being transparent, giving users control, and aligning AI with consumer interests.

    FAQ

    Q: Does the 48% trust statistic mean nearly half of consumers will buy anything an AI recommends?
    A: No. The statistic reflects conditional trust — consumers may trust AI for some products but not others, and trust doesn’t always translate to purchase behavior. People might say they trust AI but still rely on human reviews or friends.

    Q: What kinds of AI recommendations are included in this statistic?
    A: The statistic covers product recommendations specifically (e.g., retail, e-commerce), not high-stakes decisions like medical, financial, or legal advice. Trust is generally higher for low-risk purchases.

    Q: Why are younger consumers more trusting of AI recommendations?
    A: Younger consumers (18–34) grew up with algorithmic feeds on platforms like Netflix and Spotify, so they’re more familiar with AI-driven suggestions and have seen them work well over time.

    Q: Can AI recommendations be biased?
    A: Yes. Algorithms trained on historical data can perpetuate existing biases, leading to unfair or discriminatory recommendations. This is one of the key concerns raised by skeptics.

    Q: What can companies do to increase trust in their AI recommendations?
    A: Companies can build trust by being transparent about how recommendations are made, giving users control to adjust or opt out, maintaining a good track record, and ensuring the AI is aligned with consumer interests rather than just seller profits.
  • Agentic AI Shopping: Your AI Assistant Can Now Buy Things for You

    Agentic AI Shopping: Your AI Assistant Can Now Buy Things for You

    Imagine asking your phone to find a birthday gift for under $50, compare prices across five stores, read reviews, and place the order—all while you make coffee. That’s the promise of agentic AI, a new wave of artificial intelligence that doesn’t just suggest products but actually completes purchases on your behalf. In early 2025, OpenAI launched Operator, a tool that can browse the web, fill out forms, and click ‘buy’—and Google, Amazon, and Perplexity are racing to release similar features. This isn’t a futuristic fantasy; it’s arriving in beta versions right now.

    But what exactly is agentic AI, and why does it matter for shopping? Unlike the chatbots that recommend sneakers or answer ‘What’s the best laptop?’—which only talk—agentic AI acts. It can navigate websites, compare prices, negotiate with sellers, track packages, and even initiate returns. For consumers, this could mean reclaiming hours lost to online shopping drudgery. For retailers, it’s a double-edged sword: agents might boost sales or destroy profit margins by intensifying price competition. Understanding this shift is crucial for anyone who shops online—which is nearly all of us.

    From Chatbots to Agents: The Evolution of Shopping AI

    To understand agentic AI, think of the difference between a travel agent who gives you a list of flights and one who books the ticket, reserves the hotel, and emails you the itinerary. Early shopping AI was the first kind—chatbots that answered questions and made recommendations. They were passive. You did the clicking and the buying.

    Agentic AI is the second kind. It’s built on large language models (LLMs) that can not only understand language but also use tools: browsing the web, filling out forms, and clicking buttons. This leap became possible when AI systems gained ‘tool use’ capabilities—like function calling and web browsing—and computer vision improved enough for agents to ‘see’ a webpage and interact with it just like a human would. The result is software that can perform a multi-step task with minimal human oversight.

    For example, Amazon’s Rufus AI assistant isn’t just a chatbot; it can execute ‘Buy for Me’ features, completing purchases on other websites. Klarna’s AI assistant handles two-thirds of customer service chats, resolving issues without human intervention. These are early glimpses of a broader trend: AI that doesn’t just help you shop—it shops for you.

    What Agents Can Actually Do (and What They Can’t)

    Current agentic shopping tools are impressive, but they’re not fully autonomous. They’re ‘human-in-the-loop’ by design, meaning they ask for confirmation before finalizing a purchase. Still, their capabilities are expanding rapidly:

    • Browse and compare: Agents can visit multiple retailers, check prices, and compile a comparison—like a personal shopper who checks every store in the mall.
    • Fill out forms: They can input shipping and payment details into checkout forms, saving you from typing your address for the hundredth time.
    • Negotiate: Some agents can interact with sellers on platforms like eBay or Etsy, making offers on your behalf.
    • Track and manage: After a purchase, agents can monitor shipping, remind you of delivery dates, and even initiate returns if something goes wrong.

    But there are limits. Agents still make mistakes—clicking the wrong size, misunderstanding a return policy, or falling for a phishing page. They also require access to your personal and payment data, which raises privacy concerns. And because they’re optimized by the companies that build them, there’s a risk they might subtly steer you toward products that benefit the retailer, not you.

    The Retailer’s Dilemma: Friend or Foe?

    For retailers, agentic AI is a double-edged sword. On one hand, agents could reduce cart abandonment—that notorious moment when a shopper leaves items in the cart and never returns. An agent that completes the purchase could boost conversion rates significantly. They can also handle customer service at scale, as Klarna demonstrates, cutting costs dramatically.

    On the other hand, agents that compare prices across competitors could intensify price wars. If your AI can instantly find the same product $5 cheaper elsewhere, retailers lose the loyalty edge they once had. Products become commoditized, and profit margins shrink. Retailers may need to make their websites ‘agent-friendly’—using structured data and APIs so agents can easily interact—or risk being bypassed entirely. There’s also the threat of agents scraping inventory data and creating artificial demand spikes that disrupt supply chains.

    Platforms like Amazon, Google, and Shopify are racing to become the default ‘agent layer’ between consumers and merchants. Whoever controls the agent controls the shopping journey—and the data that comes with it. A key battle is whether agents will be walled gardens (Amazon’s agent only shops on Amazon) or open ecosystems (an agent that shops anywhere). Early signs suggest a mix: Amazon’s agent is restricted, while OpenAI’s Operator and Perplexity’s ‘Buy with Pro’ aim to work across the web.

    The Consumer Trade-Off: Convenience vs. Control

    For consumers, the appeal is obvious: time savings. A 2023 survey found that the average online shopper spends hours per week comparing prices and reading reviews. An agent could collapse that into minutes. For people with disabilities or those less comfortable with technology, agents could make online shopping accessible in ways previously impossible.

    But there are real risks. Losing control over purchases can be unsettling—what if the agent misinterprets ‘gift for a friend’ and buys something inappropriate? Privacy is another concern: to shop for you, an agent needs your address, payment details, and browsing history. That’s a lot of sensitive data in the hands of an AI. And there’s the erosion of browsing as leisure. Many people enjoy the hunt of finding a deal or discovering unexpected products. If AI does all the work, that joy disappears—and you might end up with exactly what you asked for, but nothing you didn’t know you wanted.

    The ethical dimension is thorny. Are agents truly acting in your best interest, or are they subtly nudging you toward higher-margin items? Without transparency, you can’t tell. The EU AI Act and consumer protection laws like the FTC’s rules on dark patterns offer some guardrails, but no specific regulations exist yet.

    The Push for Reliability and Security

    One of the biggest challenges is reliability. Agents make mistakes, and in shopping, mistakes cost money. If an agent books a non-refundable flight for the wrong date, who’s responsible? Developers are working on benchmarks like WebArena and GAIA to measure agent performance, but these are still immature. Security is another concern: agents are vulnerable to ‘prompt injection’ attacks, where malicious websites trick the AI into doing something harmful, like revealing your credit card number.

    To address these issues, tech companies are developing standardized protocols like A2A (agent-to-agent) and MCP (Model Context Protocol) to ensure agents can communicate safely with each other and with websites. But these are early days, and widespread adoption is years away.

    The Future: What to Expect in the Next Five Years

    The AI agents market is projected to grow from about $5 billion in 2024 to over $47 billion by 2030—a tenfold increase. That growth will be driven by improvements in reliability, security, and interoperability. In the near term, expect to see agentic shopping tools become more common in beta features of major platforms. Amazon’s Rufus and OpenAI’s Operator will likely expand their capabilities, and more startups will enter the space.

    But don’t expect full autonomy anytime soon. Human oversight will remain essential for high-stakes purchases. The most likely future is a hybrid: you’ll use agents for routine purchases—groceries, household items, reordering your favorite shampoo—but you’ll still personally handle big-ticket items like a house or a car, at least for the next few years.

    Eventually, agentic AI could transform the entire shopping experience. You might have a personal AI that learns your taste, manages your budget, and negotiates with retailers on your behalf. It could even handle returns and warranty claims automatically. But that future depends on solving the trust and technical challenges first. Until then, approach agentic shopping with cautious optimism: use it for low-stakes purchases, keep an eye on what it’s doing, and always double-check the final price.

    Agentic AI is not a gimmick—it’s a fundamental shift in how we interact with online commerce. By moving from recommendation to execution, these systems promise to save time and money, but they also raise serious questions about control, privacy, and fairness. As this technology matures, the smartest approach is to stay informed, start small, and remember that you’re still the boss. The AI may do the shopping, but you make the final call.

    Summary

    • Agentic AI can autonomously perform multi-step shopping tasks: browsing, comparing, purchasing, tracking, and returning—unlike chatbots that only recommend.
    • Major players: OpenAI’s Operator, Google’s Project Mariner, Amazon’s Rufus, and Perplexity’s ‘Buy with Pro’ are early examples.
    • For consumers, the trade-off is convenience vs. control: time savings come with privacy risks and potential loss of browsing enjoyment.
    • Retailers face a dilemma: agents could boost conversion rates or intensify price competition, forcing them to adapt to ‘agent-friendly’ interfaces.
    • The market is projected to grow from $5B in 2024 to $47B by 2030, but reliability and security remain major hurdles.

    FAQ

    Q: What is agentic AI?
    A: Agentic AI refers to AI systems that can autonomously perform multi-step tasks, make decisions, and take actions on behalf of a user—like browsing, comparing prices, and completing purchases—rather than just providing recommendations.

    Q: How is agentic AI different from a regular chatbot?
    A: A chatbot responds to queries with information or suggestions, but it doesn’t act. Agentic AI goes further by executing tasks—for example, it doesn’t just say ‘here are shoes,’ it says ‘I bought you shoes.’ It has autonomy and can complete a sequence of actions.

    Q: Is agentic shopping fully autonomous today?
    A: No. Current agents are ‘human-in-the-loop’ by design—they ask for confirmation before finalizing purchases. Full autonomy for high-stakes transactions is likely years away.

    Q: What are the risks of using agentic AI for shopping?
    A: The main risks are loss of control, privacy concerns (agents need access to personal and payment data), potential manipulation (agents might be optimized for retailer profit), and technical errors that could cost money.

    Q: Will agentic AI replace human shopping entirely?
    A: Not in the near term. It will likely handle routine purchases, but big-ticket items like houses or cars may still require human judgment and oversight. The future is a hybrid approach where AI handles the mundane tasks and humans focus on complex decisions.

  • How to Quit Your 9-to-5 in 12 Months: 6 Proven Strategies

    How to Quit Your 9-to-5 in 12 Months: 6 Proven Strategies

    The idea of quitting your day job within a year isn’t just a fantasy—it’s a structured goal that thousands of professionals have achieved. The 12-month timeline, popularized by books like Quit Like a Millionaire and The 4-Hour Workweek, offers a realistic yet ambitious runway. It’s not about getting rich quick; it’s about systematically building an alternative income stream that can replace your salary, while de-risking the leap.

    Here’s the reality: the average side hustler in the U.S. earns about $891 per month, according to a 2023 Bankrate survey. That’s far from a full paycheck. So, the strategies below aren’t about working harder—they’re about working smarter, focusing on the highest-leverage moves that can actually close the gap between your current income and your freedom number.

    1. The Skill Arbitrage Strategy: Sell What You Already Know

    The fastest way to generate income is to package your existing corporate skills—marketing, finance, coding, HR, design—and sell them as a freelancer or consultant. You don’t need to learn a new trade or build a product from scratch. Your network is already a warm lead pool.

    Why it works: You skip the learning curve and the slow business development phase. You can land your first client within a week by simply emailing former colleagues or posting on LinkedIn.

    Example: A marketing manager at a tech company starts taking on small social media consulting projects on the side. Within 6 months, she’s earning $2,000 a month—enough to cover half her salary. By month 12, she’s replaced her full income and quits to consult full-time.

    Watch out for: The trap of trading one boss for many. Freelancing can feel like the same grind, just with more clients. Set boundaries and raise your rates as you gain traction.

    2. The Digital Product Strategy: Create Once, Sell Repeatedly

    Instead of trading time for money, build a digital product—an online course, an ebook, a SaaS tool—that can be sold to an unlimited number of customers. This is the path to true passive income, but it’s rarely passive at the start. Expect 6–18 months of intense creation and marketing before you see significant revenue.

    Why it works: Once the product is built, the marginal cost of each sale is near zero. A $50 ebook sold to 200 people a month is $10,000 in monthly revenue.

    Example: A former teacher creates a course on “Classroom Management for New Teachers” and sells it on Udemy. In the first year, it earns $500/month; by year two, it’s $3,000/month—enough to quit her teaching job.

    Watch out for: The market is crowded. Your product must solve a specific, painful problem better than existing options. Don’t build in a vacuum—validate your idea with presales or waitlists before investing months of work.

    3. The E-Commerce Strategy: Sell Physical Products Online

    Dropshipping or private label selling on platforms like Amazon or Shopify has a low barrier to entry. You don’t need to hold inventory (dropshipping) or you can create a simple branded product (private label). This strategy can scale quickly but requires sharp marketing skills and the ability to navigate platform fees and competition.

    Why it works: The global e-commerce market is massive, and consumers are comfortable buying from small brands. You can test products with minimal upfront capital.

    Example: A fitness enthusiast starts a dropshipping store selling resistance bands. After a few failed products, he hits on a bestseller—a portable pull-up bar. He reinvests profits into Facebook ads, and by month 12, the store clears $5,000/month in profit, allowing him to leave his warehouse job.

    Watch out for: Margins can be thin, and you’re at the mercy of suppliers and platform algorithms. Avoid the common mistake of selling generic dropshipped items from AliExpress—the market is saturated. Instead, focus on a niche with a passionate audience.

    4. The Real Estate Strategy: House Hacking or Short-Term Rentals

    Real estate can provide both cash flow and long-term appreciation, but it requires capital and effort. House hacking—buying a multi-unit property, living in one unit, and renting out the others—can drastically reduce your living expenses, effectively lowering the income you need to quit. Short-term rentals (like Airbnb) can generate higher monthly revenue than long-term leases but come with more management.

    Why it works: Real estate is a tangible asset that builds equity, and rental income is often more stable than business income. The 2021–2022 housing boom also created opportunities for refinancing and equity extraction.

    Example: A software engineer buys a duplex using an FHA loan with 3.5% down. He lives in one unit and rents the other for $1,500/month, covering most of his mortgage. His living costs drop by $800/month, meaning he needs less income to quit his job. After a year, he adds a short-term rental in a nearby city, generating an additional $2,000/month.

    Watch out for: Real estate is illiquid and requires active management unless you hire a property manager (which eats into profits). Market downturns can hurt occupancy and rents. Start small and conservative.

    5. The Investment Strategy: Dividend Stocks and Index Funds

    This is the slowest but most reliable path. By investing aggressively for 12 months, you won’t achieve financial independence, but you can build a meaningful side income. Focus on dividend-paying stocks or index funds with a focus on growth. The 4% rule—withdrawing 4% of your portfolio annually—is the FIRE movement’s benchmark, but for a 12-month plan, you’re just trying to generate a supplemental income.

    Why it works: It’s passive and low-maintenance. You don’t need to be an expert; a simple S&P 500 index fund has historically returned ~7–10% annually. With a $50,000 investment, you could generate $3,500–5,000 in dividends per year, or about $300–400/month.

    Example: A project manager with a $30,000 savings account moves it into a dividend-focused ETF. By month 12, he’s earning $150/month in dividends. It’s not enough to quit, but combined with a small freelance side gig, it tips him over his income replacement threshold.

    Watch out for: This strategy won’t get you to quit in 12 months alone unless you have a large lump sum. It’s best used as a supplement to other income streams or as a long-term play after you’ve already quit.

    6. The Lifestyle Design Strategy: Cut Expenses, Not Just Income

    Instead of focusing solely on the income side, reduce your expenses so you need less money to live. This can be done through geo-arbitrage (moving to a cheaper location), minimalism, or van life. The goal is to lower your “freedom number”—the monthly income you need to cover your basic costs.

    Why it works: It’s the fastest way to close the gap between your income and expenses. If you can cut your monthly spending from $5,000 to $3,000, you only need to replace $3,000 in income, not $5,000.

    Example: A graphic designer moves from San Francisco to a small town in Portugal, where her rent drops from $2,500 to $800. She also downsizes her lifestyle: no more $200/week dining out. Her monthly expenses fall from $6,000 to $2,500. She then takes on a part-time remote design contract that pays $3,000/month—and quits her full-time job.

    Watch out for: This approach may not match your desired lifestyle. But it gives you freedom sooner, and you can always move back when your income grows. It’s not about deprivation; it’s about intentionality.

    Quitting your 9-to-5 in 12 months is ambitious, but achievable with the right mix of strategy, discipline, and a willingness to adapt. The most successful escapes combine income-building with expense-cutting, and they always build an emergency fund first—ideally 6–12 months of expenses. Start with one strategy, master it, then layer on a second. The journey may be demanding, but the payoff is a life designed on your terms.

    Summary

    • Blend income and expense strategies: Combine a side income with lifestyle cuts to close the gap faster.
    • Skill arbitrage is the fastest path: Sell your existing corporate expertise as a freelancer to get cash flow quickly.
    • Digital products offer true scalability: Create once, sell repeatedly, but expect a 6–18 month ramp-up.
    • E-commerce requires niche focus: Avoid generic dropshipping; target a specific audience with a unique product.
    • Real estate lowers expenses and builds equity: House hacking can cut your living costs and generate rental income.
    • Investments are a slow supplement: Use dividends or index funds as a secondary stream, not a primary strategy in 12 months.
    • Emergency fund is non-negotiable: Aim for 6–12 months of expenses before you quit.
    • Health insurance and taxes are the hidden hurdles: Plan for ACA/COBRA costs and self-employment taxes, which can be 15–30% of income.

    FAQ

    Q: Can I really quit my job in 12 months with these strategies?
    A: Yes, but it requires a focused effort. Most side hustles don’t replace a full salary on their own—the average side hustler earns just $891/month. The key is to combine multiple strategies, like freelancing (which brings in money fast) with digital products (which scale), and to cut expenses so you need less income.

    Q: How much money do I need saved before quitting?
    A: Financial experts recommend at least 3–6 months of expenses, but many successful quitters advocate for 12 months. This buffer protects you from income volatility and gives you time to adjust if your new income stream dips.

    Q: What about health insurance?
    A: In the U.S., this is the biggest logistical challenge. Options include COBRA (though expensive), ACA marketplace plans (subsidized based on income), or joining a spouse’s plan. In countries with universal healthcare, this is less of a concern.

    Q: How do taxes change when I quit?
    A: You move from having taxes withheld from your paycheck to paying self-employment tax and quarterly estimated payments. Many new entrepreneurs underestimate this by 15–30% of income, so set aside a portion of every payment for taxes.

    Q: What’s the best strategy for someone with no business experience?
    A: Start with skill arbitrage. Offer a service you already know how to do—like writing, graphic design, or admin support—on platforms like Upwork or Fiverr. It’s the lowest-risk way to generate income quickly, and you can learn business skills along the way.