Imagine a world where high-speed internet is as available as the air you breathe no cables, no towers, just a clear line to the sky. That’s the promise of satellite mega-constellations: networks of thousands of small spacecraft in low Earth orbit beaming broadband to every corner of the globe. For years, the idea was dismissed as financially absurd. In the 1990s, Iridium spent over $5 billion on just 77 satellites and went bankrupt. Today, Starlink has over 7,000 satellites in orbit, serves millions of customers, and is expanding rapidly. What changed? The cost of building and launching satellites has plummeted, making mega-constellations not just feasible, but one of the most transformative tech trends of the decade.
This isn’t just about convenience. About 2.6 billion people roughly a third of humanity still lack internet access. Satellite constellations could bridge that digital divide, connecting remote schools, clinics, and businesses. They also promise lower latency for global communications, critical for finance, emergency response, and even gaming. The shift from a handful of expensive geostationary satellites to swarms of cheap, replaceable ones is a revolution in how we think about space and connectivity.
But this revolution comes with costs of its own: light pollution that threatens astronomy, space debris that could clog orbits, and the risk of a few companies monopolizing access to space. Understanding how these constellations got cheap is key to grasping both their potential and their pitfalls.
The Old Space Model: Few, Big, and Pricy
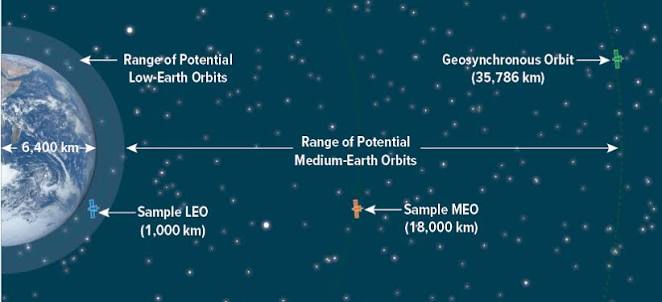
For decades, communication satellites were behemoths. Parked in geostationary orbit (GEO), about 35,786 kilometers above Earth, they could cover a continent with a single spacecraft. But each one cost over $50 million to build, plus tens of millions to launch on a once-use rocket. They had to work flawlessly for 15–20 years because replacing them was so expensive. Internet via satellite was slow, had latency over 600 milliseconds (making video calls painful), and cost a fortune for consumers.
This old model limited satellite internet to niche uses like cruise ships and military outposts—where money was no object. It simply couldn’t scale to serve billions of people.
The New Space Model: Many, Small, and Disposable
The new model flips everything. Instead of a few giant satellites, you build thousands of small ones in low Earth orbit (LEO), just 300–1,200 kilometers up. They zip around the planet every 90 minutes, so you need a whole fleet to ensure continuous coverage like a relay race where each runner hands off the baton. This architecture cuts latency to 20–50 milliseconds, comparable to ground fiber. But the real breakthrough is cost.
- Reusable rockets: SpaceX’s Falcon 9 has slashed launch costs from about $65,000 per kilogram to around $2,700. The upcoming Starship aims for under $1,000, making it cheaper to put mass in orbit than ever before.
- Mass production: Satellites are now built on assembly lines, like cars. Starlink v1 satellites cost roughly $250,000–$500,000 each; even the beefier v2 mini runs about $1 million. In the old GEO days, a single satellite cost over $50 million. That’s a 50- to 100-fold drop.
- Miniaturization: CubeSat standards and flat-panel designs have shrunk satellites from bus-sized to microwave-sized, making them cheaper to build and launch.
- Smart antennas: Phased array antennas steer beams electronically, no moving parts needed. This cuts weight and maintenance.
- Laser links: Inter-satellite laser links let data hop between spacecraft in space, reducing reliance on ground stations and enabling true global routing.
These innovations have driven the cost per gigabit per second (Gbps) of capacity down by roughly 100 times in a decade. That’s the economic engine behind the mega-constellation boom.
Who’s Building Them? A Snapshot
| Operator | Planned Size | Launched (approx.) | Status |
|———-|————–|——————–|——–|
| Starlink (SpaceX) | ~42,000 | ~7,000+ | Active in 100+ countries |
| OneWeb (Eutelsat) | ~648 | ~640 | Commercial since 2023 |
| Amazon Kuiper | ~3,236 | ~2 prototypes | Launching 2025–2026 |
| Telesat Lightspeed | ~198 | 0 | Delayed, targeting 2027 |
| Guowang (China) | ~13,000 | ~100+ | Early deployment |
| G60 Qianfan (China) | ~15,000 | ~100+ | Early deployment |
Starlink leads by a wide margin, with about 5 million subscribers and $8 billion in annual revenue as of 2025. Its vertical integration—building its own satellites, rockets, and ground terminals—gives it a cost edge that rivals can’t easily match. For example, a Starlink launch on a Falcon 9 rideshare might cost $100,000–$200,000 per satellite, a fraction of the total unit cost.
The SpaceX Disruption: A Monopoly in the Making?
SpaceX’s combination of reusable rockets and in-house satellite production is a powerful flywheel. Each Falcon 9 launch can carry 50–60 Starlink satellites, and the rocket’s first stage is reused multiple times, spreading costs across missions. The next step is Starship, a fully reusable super-heavy rocket with a 100–150-ton payload capacity. If Starship reaches its target of under $1,000 per kilogram, it could enable Starlink’s full 42,000-satellite architecture—and make launch costs a rounding error.
But this dominance raises red flags. SpaceX controls both the launch vehicles and the satellite service, giving it a chokehold on the emerging space economy. Antitrust concerns and national security worries (what if a foreign power relies on a US company for internet?) could lead to regulation or pressure to open up access.
The Challengers: Can Anyone Catch Up?
- Amazon Kuiper is the most direct competitor. It’s betting on larger, more capable satellites, but lacks an in-house rocket. It will rely on Atlas V, Vulcan, and Ariane 6 for launches, which are pricier. Kuiper must deploy 50% of its constellation by 2026 to keep its FCC license, a tight deadline.
- OneWeb targets enterprise and government customers rather than consumers. Its satellites operate in a polar orbit at 1,200 kilometers, giving it a different coverage pattern. With Eutelsat’s backing, it focuses on reliability over raw scale.
- China’s Guowang and G60 Qianfan are state-backed programs aimed at strategic autonomy. They plan to launch thousands of satellites, but their progress is slower. However, with the Long March 5 and future reusable rockets, they could scale rapidly.
Each challenger has a different playbook, but all face the same hurdle: matching Starlink’s cost structure without their own reusable rocket fleet.
Why This Matters: The Digital Divide and Beyond
The promise of mega-constellations is universal connectivity. For a farmer in rural Kenya or a student in a remote Peruvian village, satellite internet could be their first reliable link to the world. Starlink is already active in over 100 countries, and OneWeb is providing connectivity to schools and clinics in Africa. The technology is also critical for industries like maritime, aviation, and emergency response, where ground infrastructure is absent or fragile.
But there are trade-offs. The cost of ground terminals has dropped (Starlink’s dish now costs around $200–$500), but that’s still a hurdle for low-income users. And while the constellations are getting cheaper to build, the overall investment is staggering—Starlink’s program cost has hit $20–30 billion already, and could reach $50 billion by 2030. That means companies need millions of subscribers to break even, which could keep prices higher than ideal for the world’s poorest.
The Dark Side: Astronomy, Debris, and the Environment
Mega-constellations have a significant downside. Astronomers are alarmed: satellite trails streak across telescope images, interfering with scientific observations. The Vera Rubin Observatory, set to map the night sky, is particularly vulnerable. Radio astronomy is also affected by the RF signals these satellites emit, which can drown out faint cosmic whispers.
Then there’s space debris. With tens of thousands of satellites planned, the risk of collisions rises. Kessler Syndrome—a chain reaction where one crash creates debris that hits more satellites—could render low Earth orbit unusable. To address this, the FCC now requires satellites to deorbit within five years of end of life, and operators are adding maneuvering capabilities. But the sheer number means accidents will happen.
Finally, the environmental impact of launching and re-entering thousands of satellites is still not fully understood. Re-entry burns up spacecraft in the atmosphere, potentially releasing materials that could affect the ozone layer. The long-term consequences are unknown, and regulators are scrambling to keep up.
Regulatory Squeeze: Use It or Lose It
A patchwork of national and international rules governs these constellations. The FCC, for instance, requires operators to deploy a percentage of their satellites within six years of licensing, or lose their slots. The ITU (International Telecommunication Union) coordinates spectrum and orbital slots, with a “use it or lose it” policy that pushes companies to launch fast. This regulatory pressure is why we’re seeing rapid deployment, but it also creates a rush that can lead to mistakes—like satellites failing or colliding.
Orbital debris rules are tightening too. The FCC’s 5-year deorbit rule is a start, but as constellations grow, we’ll need more robust traffic management in space. Some propose an international space traffic organization, but that’s a long way off.
What’s Next: The Road to Full Coverage
By 2030, we could have 100,000 satellites in orbit, blanketing the Earth with connectivity. Starship could make launch costs negligible, enabling even bigger constellations. But the industry must balance speed with responsibility. The key will be sustainable practices: designing satellites for easy deorbit, using materials that burn up cleanly, and coordinating with astronomers to minimize interference.
For consumers, the future is bright: more competition could drive prices down, and latency will continue to drop. Satellite internet might eventually be as common as mobile data. But we must decide how to govern this new frontier—before it’s too late.
The cost revolution in satellite mega-constellations is one of the most consequential tech stories of our time. It’s turning a failed 1990s dream into a global reality, with the potential to connect billions and transform industries. But it also comes with real risks to our night sky, our orbital environment, and our economic fairness. As these constellations expand, we’ll need smart regulation, continued innovation, and a global conversation about what we’re willing to trade for universal connectivity. The sky is no longer the limit—it’s the arena.
Summary
- Costs have plummeted: Reusable rockets (Falcon 9, Starship), mass production, and miniaturization have cut satellite costs by 50–100x, enabling mega-constellations.
- Starlink leads, others follow: SpaceX’s vertical integration and low launch costs give it a huge edge; Amazon Kuiper and China’s constellations are trying to catch up.
- Global impact: Mega-constellations can bridge the digital divide for 2.6 billion unconnected people, with low latency and wide coverage.
- Risks loom: Light pollution, space debris, and RF interference threaten astronomy and the orbital environment; regulators are scrambling to adapt.
- The future is uncertain: Full deployment could bring 100,000+ satellites by 2030, but must be managed sustainably to avoid Kessler Syndrome and other dangers.
FAQ
Q: What is a satellite mega-constellation?
A: It’s a network of hundreds to thousands (even tens of thousands) of small satellites in low Earth orbit (LEO), working together to provide global broadband internet. Unlike traditional geostationary satellites, they’re close to Earth, which reduces latency.
Q: How have costs dropped so dramatically?
A: Mainly due to reusable rockets (SpaceX’s Falcon 9 and upcoming Starship), which cut launch costs from ~$65,000/kg to under $2,700/kg. Also, satellites are now mass-produced on assembly lines, with cheap components like phased array antennas, bringing unit costs down from $50M+ to under $1M.
Q: Who are the main players?
A: Starlink (SpaceX) is the leader with over 7,000 satellites and millions of users. Others include OneWeb (Eutelsat), Amazon Kuiper, Telesat Lightspeed, and China’s Guowang and G60 Qianfan constellations.
Q: What are the downsides?
A: Three big challenges: light pollution that hampers astronomy, the risk of space debris and collisions (Kessler Syndrome), and radio frequency interference with scientific instruments. There’s also concern about the environmental impact of launches and re-entries.
Q: Will satellite internet be affordable for everyone?
A: Costs are dropping—Starlink’s dish is a few hundred dollars, and service plans are cheaper than before—but for the world’s poorest, it’s still a luxury. As competition grows and technology improves, prices may fall further, but universal affordability remains a challenge.